



Insurance for Religious Organizations, Weddings & Private Parties in Oregon
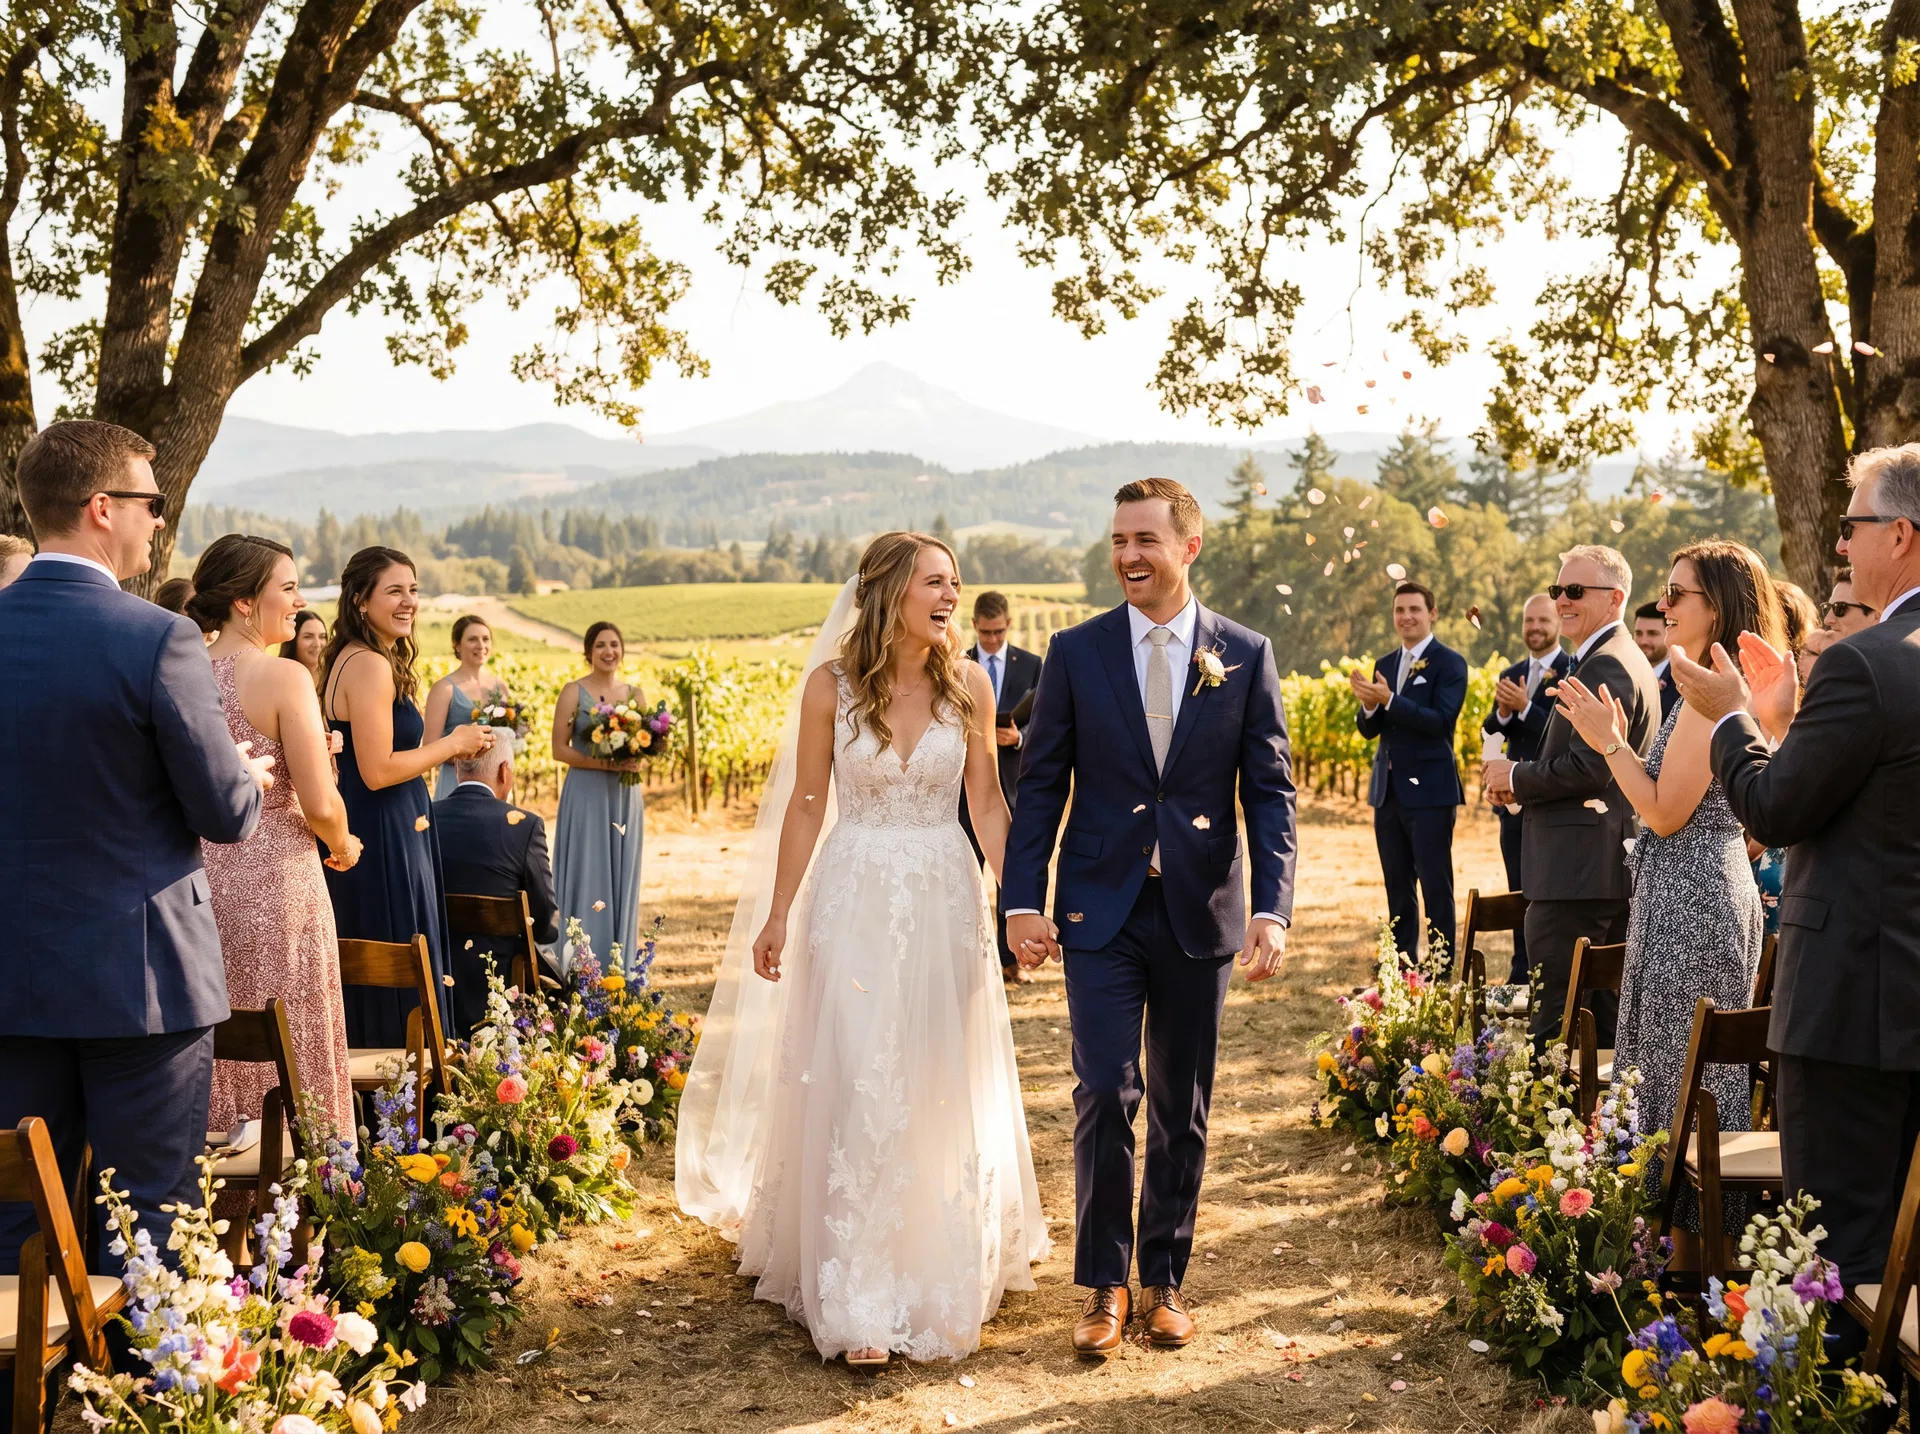
Insurance for Religious Organizations, Weddings & Private Parties in Oregon

Whether you are hosting a Sunday service, exchanging vows in a vineyard, or throwing a milestone birthday party at a rented venue, one thing is true: if something goes wrong, someone is responsible. For Oregon churches, mosques, synagogues, temples, and the families hosting life's biggest celebrations, the right insurance coverage is not a luxury — it is the difference between a manageable setback and a financial crisis.
Insure Pacific has been helping Central Oregon families, faith communities, and event organizers navigate these coverage questions since 1935. This guide breaks down exactly what coverage is needed, what it costs, and how to make sure your next gathering — sacred or celebratory — is properly protected.
Insurance for Religious Organizations: More Than Just the Building
Many church leaders and congregation administrators assume their building insurance covers everything. It does not. A comprehensive religious organization insurance program typically includes seven distinct coverage types, each addressing a different category of risk.
General Liability Insurance is the foundation of any commercial insurance program for faith-based organizations. It covers bodily injury and property damage claims arising from activities on your premises or at off-site events. If a visitor slips on a wet floor during a potluck dinner, or a youth group activity results in a broken window at a community center, general liability responds. Most Oregon venues and landlords require a minimum of $1 million per occurrence before they will allow a congregation to use their space.
Property Insurance covers the physical building, its contents, and equipment — from pews and sound systems to kitchen appliances and office computers. This is similar to the homeowners insurance that protects a private residence, but written specifically for non-residential and mixed-use religious properties. For congregations that own their building, replacement cost coverage (rather than actual cash value) is strongly recommended, particularly given the rising cost of construction materials in Central Oregon.
Directors & Officers (D&O) Liability protects board members, elders, deacons, and committee chairs from personal liability arising from decisions made on behalf of the organization. Allegations of mismanagement, breach of fiduciary duty, or employment disputes can target individual leaders personally — D&O coverage provides defense costs and indemnification.
Workers' Compensation is legally required in Oregon for any paid employees, including part-time staff, musicians, and custodians. This requirement applies to religious organizations the same as any other Oregon employer — see our small business insurance guide for more on Oregon workers' comp requirements. Volunteer workers are not covered under workers' comp, but a separate volunteer accident policy can fill that gap.
Sexual Misconduct Liability is a specialized coverage that many standard general liability policies specifically exclude. Given the pastoral care and youth ministry activities common to most congregations, this coverage is essential and should be reviewed carefully for scope and limits.
Commercial Auto covers vehicles owned by the organization — church vans, shuttle buses, and delivery vehicles. For congregations with a fleet of vehicles, this functions similarly to personal auto insurance but with commercial-grade liability limits appropriate for passenger transport. If volunteers use their personal vehicles for church activities, a non-owned and hired auto endorsement extends coverage to those situations.
Umbrella / Excess Liability provides an additional layer of protection above the underlying general liability, auto, and D&O limits. Learn more about how umbrella insurance works and why it is one of the most cost-effective ways to protect an organization from catastrophic claims. For larger congregations, schools, or organizations running multiple programs, a $1–$5 million umbrella is a cost-effective way to significantly increase total protection.
| Coverage Type | What It Covers | Typical Annual Cost |
|---|---|---|
| General Liability | Bodily injury, property damage, personal injury | $400–$1,200/yr |
| Property Insurance | Building, contents, equipment | Varies by building value |
| D&O Liability | Board member decisions, employment disputes | $500–$2,000/yr |
| Workers' Compensation | Employee injuries (required by Oregon law) | Based on payroll |
| Sexual Misconduct Liability | Abuse and molestation claims | $300–$1,500/yr |
| Commercial Auto | Owned vehicles, hired/non-owned auto | $800–$3,000/yr |
| Umbrella / Excess | Additional limits above all underlying policies | $300–$800/yr per $1M |
Oregon congregations that rent space to outside groups — yoga studios, AA meetings, community organizations — should also ensure their general liability policy covers third-party use of the premises, or require renters to carry their own event liability policy and name the church as an additional insured. Our Non-Profits & Events page has more information on coverage for faith-based organizations.
Wedding Insurance: Protecting Your Investment Before and During the Big Day
The average Oregon wedding now costs between $25,000 and $45,000. That investment deserves protection. Wedding insurance is available in two primary forms: event cancellation/postponement coverage and event liability coverage. Many couples purchase both.
Event Liability Insurance is the coverage most Oregon venues require before they will sign a contract. It protects the couple (and sometimes the venue) if a guest is injured, property is damaged, or alcohol-related incidents occur. Liability limits typically range from $500,000 to $2 million, and most Oregon venues require a minimum of $1 million. Host liquor liability — which covers incidents arising from alcohol served at the event — is a critical add-on for any reception where alcohol is served, even if a licensed bartender is handling service.
Event Cancellation / Postponement Insurance reimburses non-refundable deposits and prepaid expenses if the wedding must be cancelled or postponed due to covered reasons — vendor bankruptcy, sudden illness of immediate family members, extreme weather, or venue closure. This coverage does not apply to cold feet or voluntary cancellations, but it can recover tens of thousands of dollars in lost deposits if a covered event forces a change of plans.
| Wedding Insurance Type | What It Covers | Typical Cost |
|---|---|---|
| Event Liability ($1M) | Guest injuries, property damage, host liquor | $125–$300 |
| Event Liability ($2M) | Higher limits for larger events or venues | $200–$450 |
| Cancellation / Postponement | Non-refundable deposits, vendor failure | $160–$550 |
| Combined Policy | Liability + cancellation in one policy | $300–$800 |
Wedding insurance is typically purchased 12–18 months before the event and can be obtained up to the day before the wedding (though earlier is always better). Coverage must be in place before any incident occurs — you cannot purchase it after a vendor cancels or a guest is injured.
What wedding insurance does NOT cover: pre-existing vendor issues known at the time of purchase, cancellation due to change of mind, or incidents that occur after the event ends. For destination weddings in Oregon — popular at Crater Lake, the Columbia River Gorge, or Central Oregon ranches — travel insurance may be needed in addition to event coverage. Couples planning a ranch or farm wedding should also ask about farm and ranch insurance requirements that the venue may carry, and whether their event policy needs to align with the venue's existing coverage.
Private Party Insurance: Backyard Barbecues to Milestone Celebrations
Many Oregonians are surprised to learn that their homeowner's insurance may not fully cover a large private party — especially one where alcohol is served. A standard homeowner's policy typically provides some liability coverage for social gatherings, but limits are often inadequate for large events, and many policies contain exclusions for alcohol-related incidents or events held at rented venues.
Special Event Liability Insurance fills this gap. A one-day event policy covering a birthday party, anniversary celebration, graduation party, or family reunion typically costs between $75 and $200 for $1 million in liability coverage. Policies can be purchased for events at your home, a rented hall, a park pavilion, or any other venue.
Key situations where a standalone event policy is strongly recommended include:
Liquor Liability deserves special attention. Oregon's dram shop laws can hold a host personally liable if a guest becomes intoxicated at their event and subsequently injures a third party — even after leaving the property. This is a risk that your standard homeowner's policy is unlikely to cover adequately for large gatherings. Host liquor liability coverage, available as an endorsement on most event policies, provides critical protection in these situations.
Independent Insurance Agency Since 1935
Not Sure If You Have the Right Coverage?
Our licensed agents compare 50+ carriers to find you the best coverage at the right price — at no extra cost to you.
How Insure Pacific Can Help
As an independent insurance agency with access to more than 50 carriers, Insure Pacific can shop the market to find the right coverage for your specific event or organization. We work with specialty carriers who understand the unique needs of faith communities, event organizers, and families hosting private celebrations in Oregon.
Our team can help you:
Whether you are a congregation administrator in Bend, a bride planning a vineyard wedding in the Willamette Valley, or a family hosting a 50th anniversary party in Prineville, Insure Pacific is here to make sure your celebration is protected. For broader personal protection, consider pairing your event policy with a life insurance review — many of life's biggest milestones are also a good time to revisit your family's overall coverage picture. Contact us today for a no-obligation consultation. You can also explore our Umbrella Insurance options for additional protection above your event policy limits.
Frequently Asked Questions
Does my church need insurance if we rent our building? Yes. Your landlord's property insurance covers the building structure, but it does not cover your congregation's contents, your liability to guests, or claims against your board members. You need your own policy regardless of whether you own or rent.
How far in advance should I buy wedding insurance? As soon as you begin paying deposits — ideally 12–18 months before the wedding. The sooner you purchase, the more events are covered under the cancellation provision.
Does my homeowner's insurance cover a backyard wedding? Possibly, but with important limitations. Most homeowner's policies have liability limits of $100,000–$300,000, which may be insufficient for a large event. They also typically exclude alcohol-related incidents and events at off-premises venues. A standalone event policy is almost always the better choice.
What does an Oregon venue require for event insurance? Most Oregon venues require a minimum of $1 million in general liability coverage, with the venue named as an additional insured on the certificate. Some venues require $2 million for events over 150 guests or events serving alcohol.
Can I get same-day event insurance? Yes — most carriers offer same-day or next-day issuance for event liability policies. However, cancellation/postponement coverage cannot be purchased after a triggering event has already occurred.
Contact Insure Pacific for a free, no-obligation consultation. We'll review your specific situation and find the right coverage — fast.
Our Licensed Coverage Area
States highlighted in blue are states where Insure Pacific holds an active insurance license.
Hover to highlight — click a state to visit its insurance page
Our Oregon Office Locations
Hover over a marker to see the office — click to visit their website.
Hover to highlight — click to visit that office's website
Ready to Get Protected?
Talk to a Local Oregon Insurance Expert
Insure Pacific has been serving Oregon families and businesses since 1935. We work with 50+ carriers so you get real options — not just one company's answer.
Related Articles
 Commercial Insurance
Multi-State Workers’ Compensation: Remote Employees, Traveling Crews, and Out-of-State Jobs
Read Article → Commercial Insurance
Import and Export Cargo Insurance: Ocean Freight, Ports, Customs, and Inland Transportation
Read Article → Commercial Insurance
Has Your Business Outgrown Its Insurance? Revenue, Payroll, New Locations, and New Services
Read Article → Commercial Insurance
Buying a Commercial Building: Insurance Questions to Answer Before Closing
Read Article →Get in Touch
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


