
Residential Inspectors
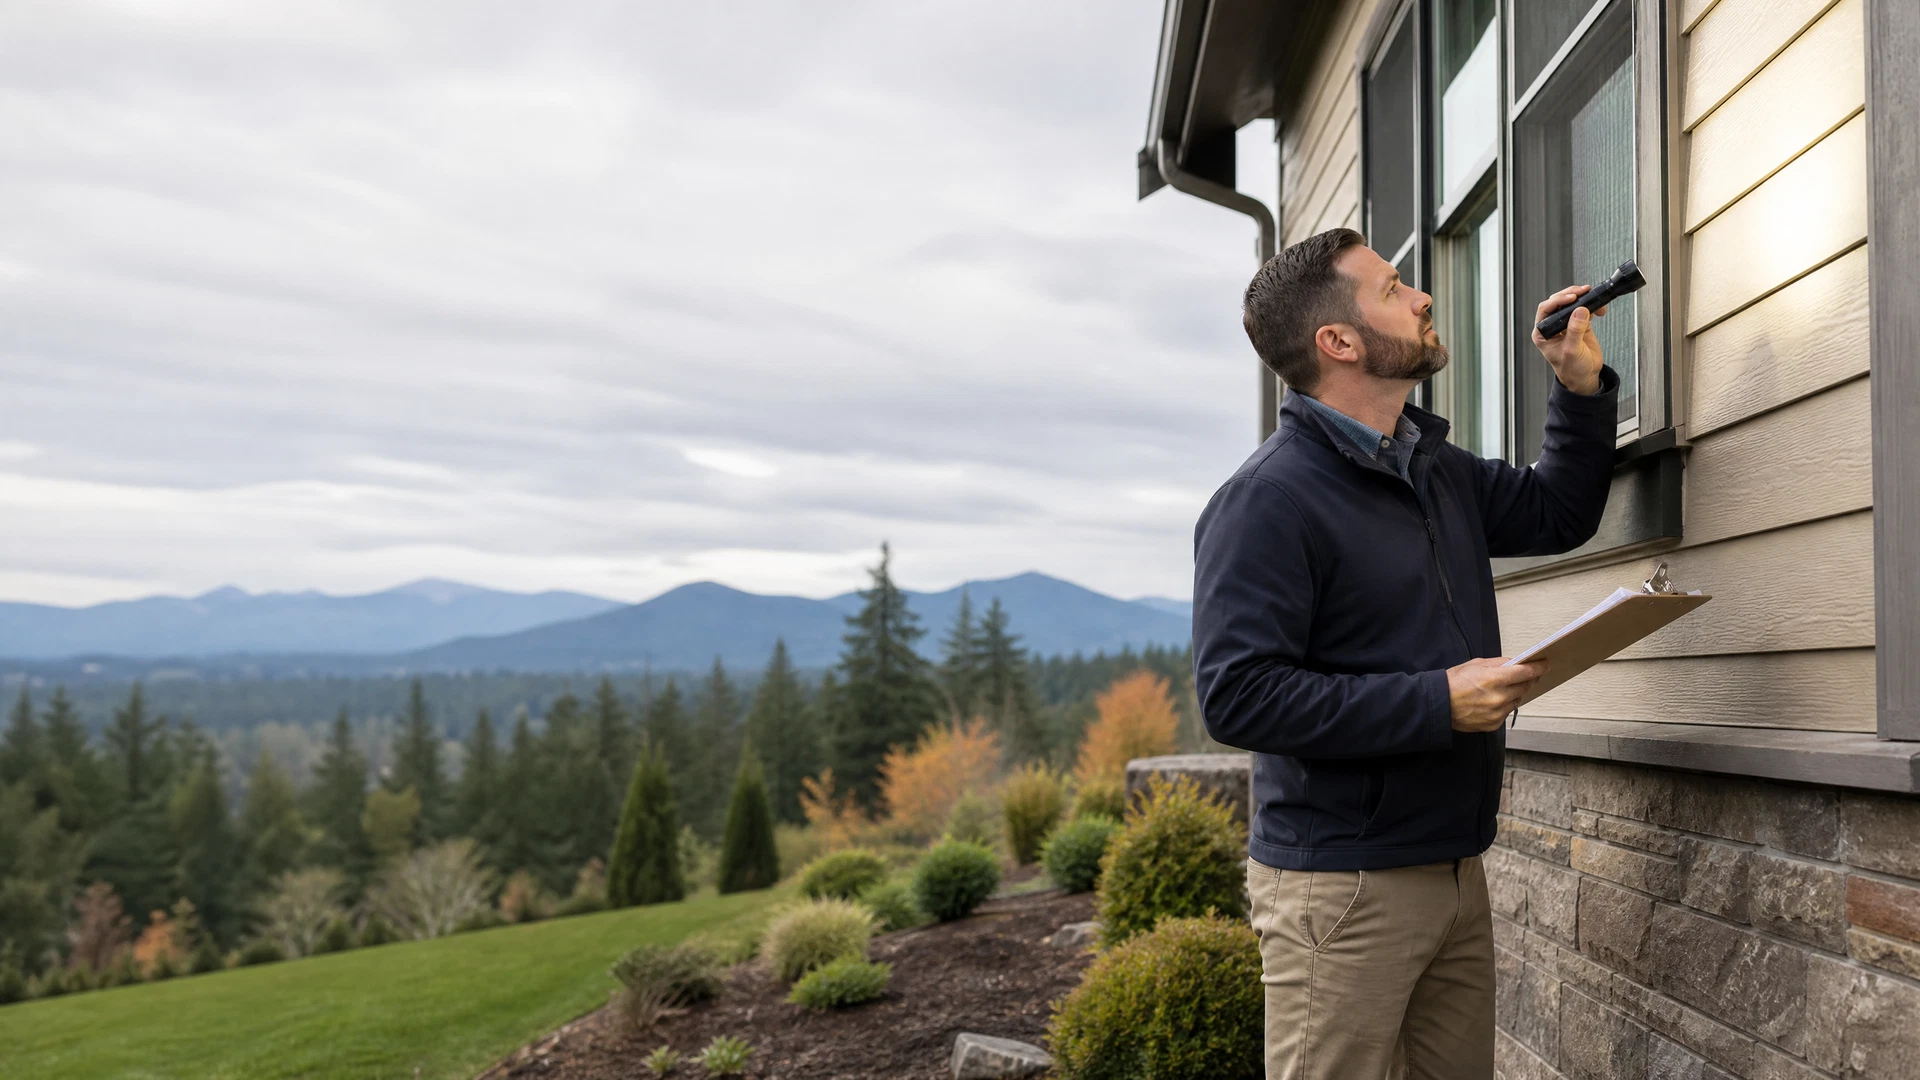
Independent inspectors evaluating homes, condominiums, townhomes, and residential properties for buyers and owners.



Professional Liability
Professional liability protection discussions for independent home inspection businesses and growing inspection firms.
Professional Protection
Home inspector insurance combines insurance discussions that support a professional whose reports influence important property decisions. A home inspector can face allegations that a condition was missed, a report was inaccurate, equipment damaged property, a client's information was exposed, or an accident occurred while conducting business.
Professional liability or errors and omissions coverage is often central to the conversation because inspection findings, exclusions, recommendations, and report delivery can become part of a client dispute. General liability, auto, equipment, cyber, workers' compensation, and umbrella policies address other distinct business exposures.
Insure Pacific helps Oregon inspection businesses compare relevant insurance options. The actual protection available depends on policy forms, endorsements, exclusions, claim facts, report language, contracts, and underwriting requirements.
Designed for Inspection Work
Independent inspectors evaluating homes, condominiums, townhomes, and residential properties for buyers and owners.
Inspectors working with builders, buyers, and owners on phased, pre-drywall, warranty, or final construction inspections.
Professionals providing ancillary services such as radon, mold, sewer scope, thermal imaging, roof, or pool inspections.
Growing inspection firms coordinating employees, subcontractors, vehicles, equipment, reports, and client communications.
Coverage Conversation
These are policy topics to review with an agent and carrier. They do not guarantee coverage; the terms, conditions, exclusions, definitions, and endorsements in an issued policy control.
Annual Risk Review
A professional insurance review should evolve with the inspection business. Before renewal, compare the policy to current services, contracts, technology, tools, travel, and client-reporting practices.
Answers for Inspectors
Home inspectors commonly discuss professional liability or errors and omissions coverage because a client may allege that an inspection missed or incorrectly reported a condition. Actual coverage depends on the policy form, report language, exclusions, limits, and facts of a claim.
No. General liability and professional liability address different types of allegations. General liability often concerns bodily injury or property damage, while E&O addresses alleged professional errors or omissions. Both should be reviewed with an agent.
Review services, report language, contracts, revenue, number of inspections, staff, vehicles, equipment, ancillary inspections, claims, and any changes in how reports or client data are managed.
Coverage for inspection equipment may be available through inland marine, tools and equipment, or business personal property coverage, subject to schedules, deductibles, valuation, theft conditions, and policy terms.
Talk with an independent agent about professional liability, reports, tools, travel, client information, and the exposures unique to your inspection practice.
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


