Insure Pacific
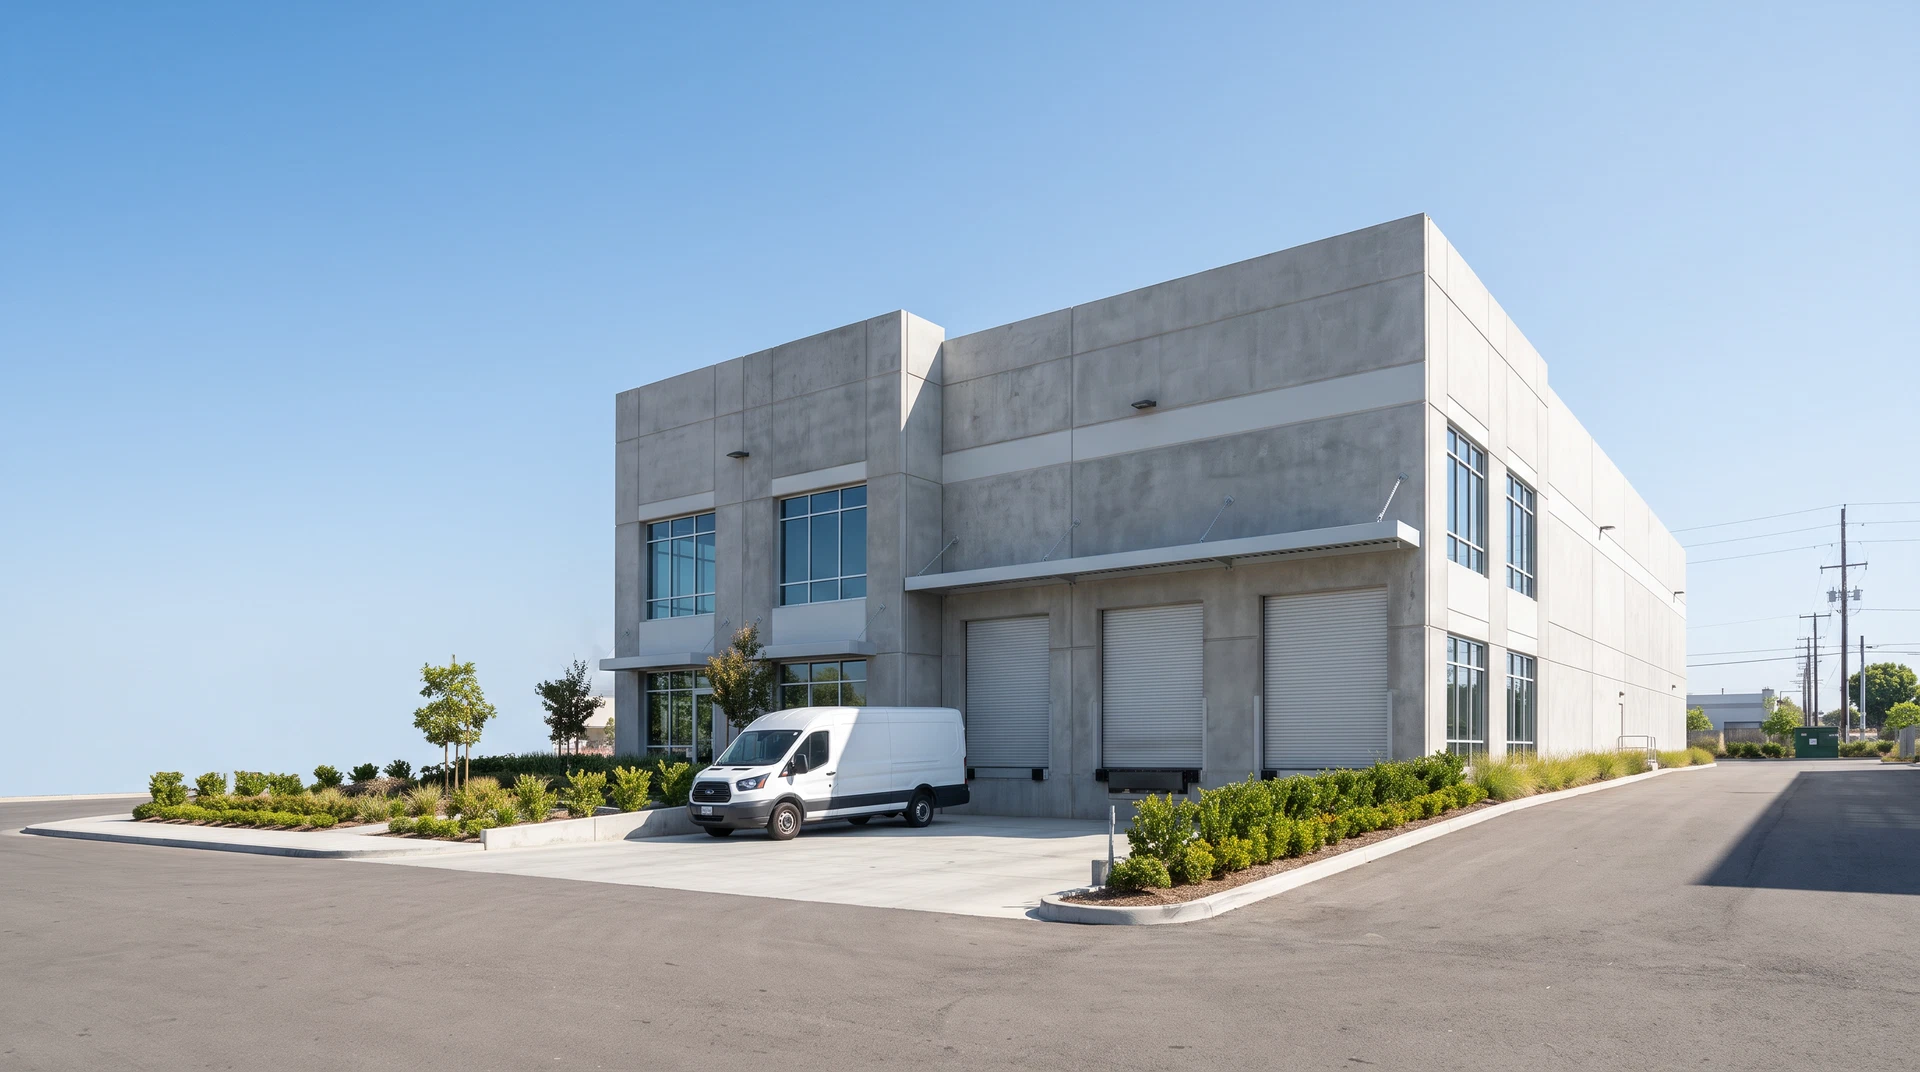
Modern light industrial flex building

COMMERCIAL COVERAGE FOR FLEX & INDUSTRIAL PROPERTY

Light Industrial Property Insurance

Coverage options for owners and operators balancing structures, tenants, loading areas, equipment, inventory, liability, and income resilience.

Insurance for a Property That Works Hard

Light industrial property can include flex buildings, contractor shops, service facilities, warehouse space, small manufacturing space, distribution areas, and mixed office-industrial occupancies. Loading doors, exterior storage, tenant improvements, machinery, and daily vehicle movement may create a risk profile that differs from a conventional office property.

A useful insurance review considers construction and replacement values, occupancy and tenant operations, roof and utility systems, loading and parking areas, fire protection, water and weather exposure, lease responsibilities, outdoor property, income dependence, and applicable lender requirements. Flood is generally a separate coverage discussion.

Insure Pacific can help compare commercial insurance options around the individual property, its operations, and its continuity priorities.


Coverage to Discuss

Commercial property for eligible buildings, improvements, and owner-owned contents
Business-income and extra-expense options following a covered interruption
General liability for premises, common areas, and visitor exposures
Equipment breakdown options for eligible electrical, HVAC, and mechanical systems
Ordinance or law options for qualifying repair or rebuilding requirements
Commercial umbrella and excess liability coverage
Cyber liability options for property, billing, and management systems
Flood review and other location-specific coverage options

Important Review Points for Light Industrial Space

A program should be revisited when acquiring, selling, refinancing, remodeling, expanding, changing tenancy or use, storing new materials, adding equipment, changing property management, or entering leases with updated insurance and certificate requirements.

Bring building values, lease allocations, tenant operations, equipment details, maintenance records, loss history, site plans, and a practical response plan for property, utility, or weather disruptions to your review.

Prepare for Your Review

  • Addresses, square footage, construction, occupancy, and current replacement-cost information
  • Tenant improvements, leases, certificates, contracts, and property-management responsibilities
  • Loading areas, machinery, HVAC, electrical, roof, fire protection, utilities, and exterior storage
  • Income, expenses, flood exposure, outdoor operations, and contingency priorities

Light Industrial Property Insurance FAQs

What is light industrial property insurance?

It is a commercial insurance discussion for industrial or flex buildings, owner-owned property, tenant operations, loading areas, systems, liability, and income exposures. Appropriate coverage depends on the particular property and business.

Do tenants need their own coverage?

Lease terms often allocate property, liability, tenant-improvement, certificate, and additional-insured requirements. Owners and tenants should review those contractual obligations with their insurance professionals.

Does commercial property insurance cover flood?

Flood is typically a separate coverage consideration. Discuss the location, lender requirements, building and contents values, and available options with your agent.

How can Insure Pacific help?

Insure Pacific is an independent agency that can help learn about your property and compare commercial insurance options from multiple carriers.

Get a Light Industrial Property Insurance Quote

Tell us about your buildings, tenants, operations, systems, values, contracts, and continuity goals.

Get in Touch

Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.

Do not send SSNs, medical records, payment details or account passwords. This inquiry does not bind or change coverage. Privacy Policy.