
Commercial Print Shops
Businesses producing marketing materials, business documents, signage, packaging, labels, direct mail, and custom print jobs.



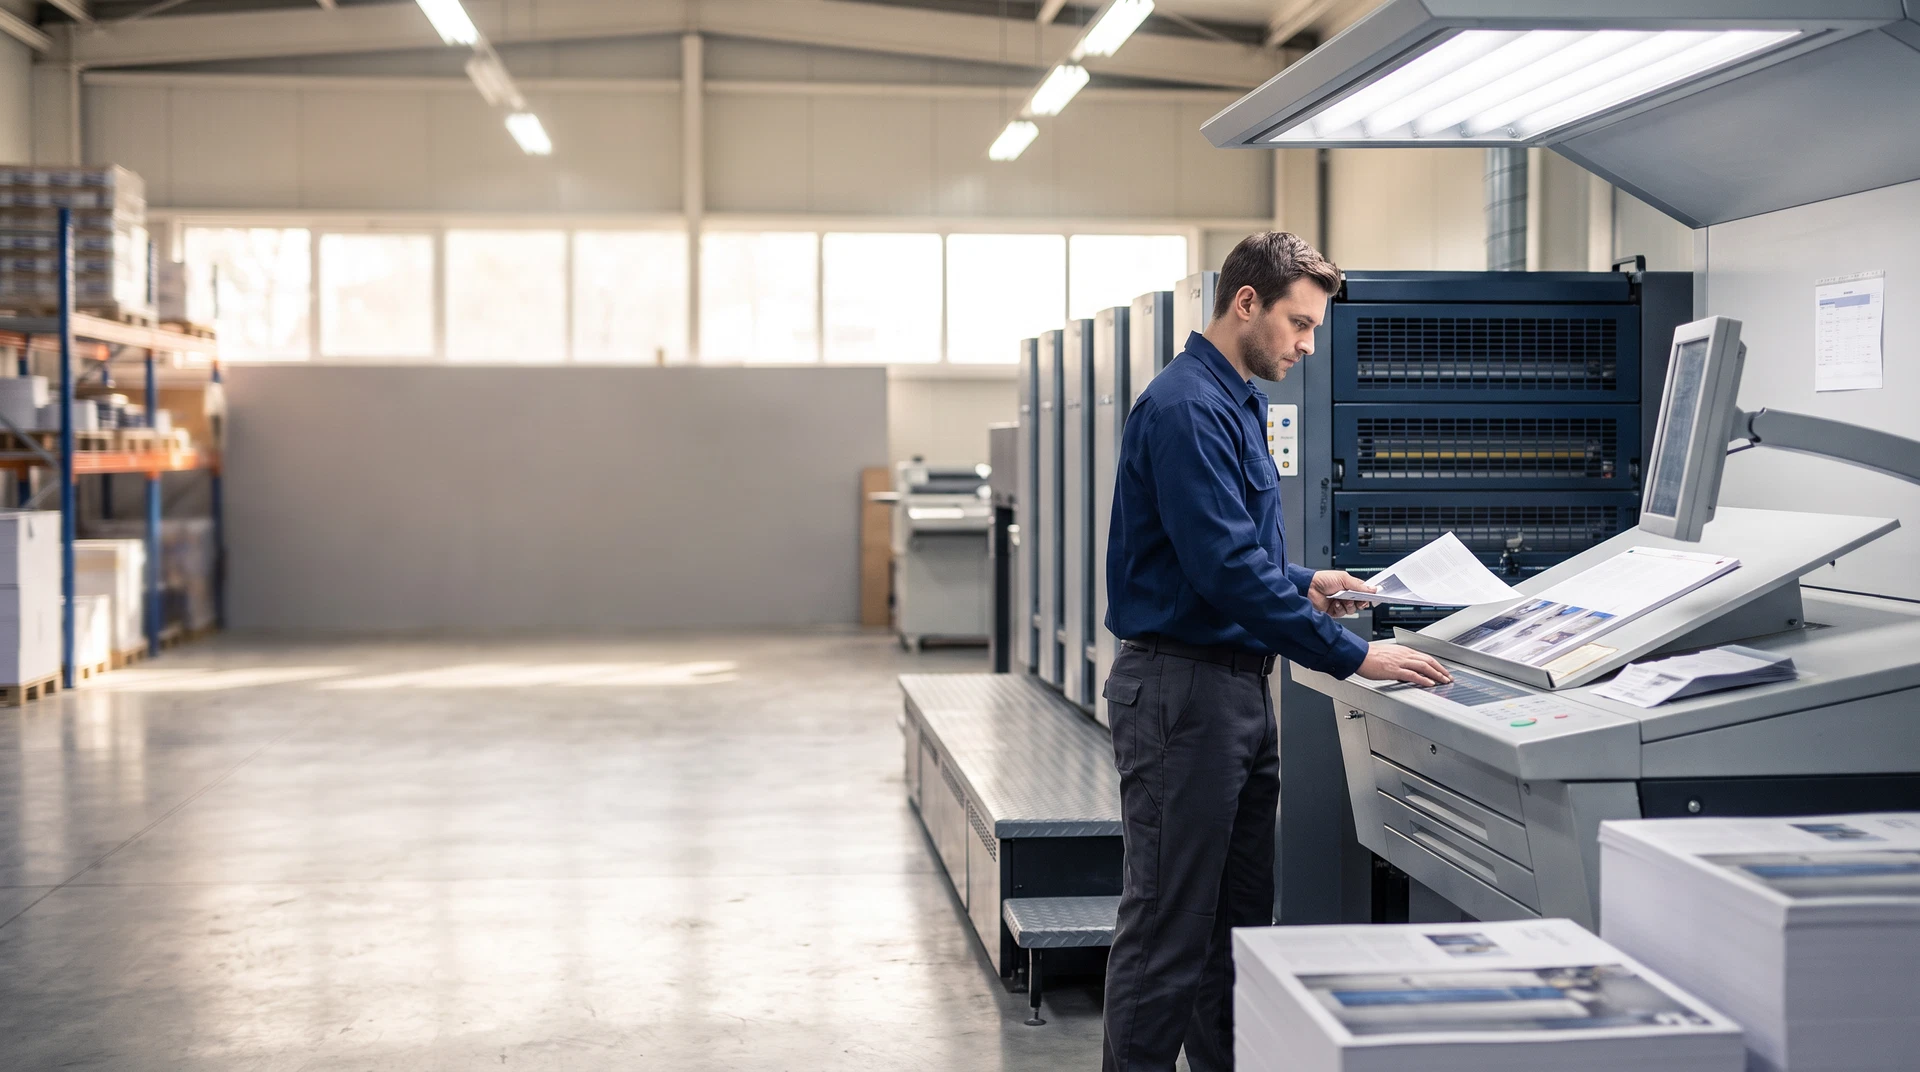
Practical protection for print shops, publishers, and production teams.
Printing and publishing insurance is a commercial insurance approach designed around production equipment, print and digital content, client files, inventory, schedules, employees, delivery, contracts, intellectual property, and business property. Your operation may design, print, publish, bind, fulfill, distribute, mail, or manage digital content and production workflows.
Because printing and publishing businesses rely on specialized presses, client materials, production systems, and content rights, property, equipment breakdown, and professional or media liability can be important discussions. Depending on your operation, general liability, auto, workers compensation, cyber, business interruption, and umbrella options may also be relevant.
Insure Pacific can help printing and publishing businesses compare independent carrier options. We begin with your services, equipment, content, contracts, staff, property, data systems, and operations so the conversation fits your production business.
A coverage review can be useful for businesses that produce printed material, publish content, manage client files, or operate specialized production equipment.
Businesses producing marketing materials, business documents, signage, packaging, labels, direct mail, and custom print jobs.
Book, magazine, newspaper, digital, educational, and specialty publishers managing content, rights, production, and distribution.
Production teams preparing client artwork, layouts, files, proofs, color management, plates, and digital assets.
Operations handling large format, screen printing, packaging, fulfillment, bindery, mailing, print-on-demand, or finishing services.
The appropriate mix depends on your production, equipment, property, employees, content, client obligations, systems, and operations.
Review eligible printing presses, finishing equipment, computers, inventory, paper, ink, supplies, tools, buildings, and business contents.
Discuss protection for certain covered mechanical or electrical breakdown involving eligible production equipment and systems.
Help address covered third-party bodily injury or property-damage claims connected to premises, products, client visits, and operations.
Consider coverage discussions for covered allegations tied to publishing, content, errors, omissions, intellectual property, or professional services.
Review coverage for owned delivery vehicles, service vehicles, parts runs, and other eligible business transportation.
Discuss coverage required for eligible employees and help address covered workplace injuries, subject to state requirements and policy terms.
Discuss protection for client files, payment data, content archives, production systems, email, cloud storage, and privacy-related events.
Review income-loss and additional-liability-limit discussions for eligible risks when a covered loss interrupts operations or greater limits are needed.
Annual policy review
Production volume, equipment, content, client contracts, inventory, staff, delivery, data systems, and property can change your business exposures. Review the details before your next renewal.
Common questions about protecting a printing, publishing, or production business.
The conversation commonly includes property, equipment, general liability, professional or media liability, cyber, workers compensation, auto, business interruption, and umbrella coverage. The appropriate mix depends on your services and operations.
Publishing can involve content, copyright, defamation, privacy, and intellectual-property exposures. Media liability may be an important discussion depending on content, distribution, contracts, and policy terms.
Equipment-breakdown options may be available for eligible presses and production systems, subject to policy terms. Review equipment age, maintenance, values, and operational dependency with your agent.
Review before renewal and whenever production, equipment, property, employees, client contracts, content, inventory, delivery, or material operations change.
Talk with an independent Insure Pacific agent about property, equipment, media liability, cyber, workforce, and commercial coverage considerations.
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


