
Cultivation Operations
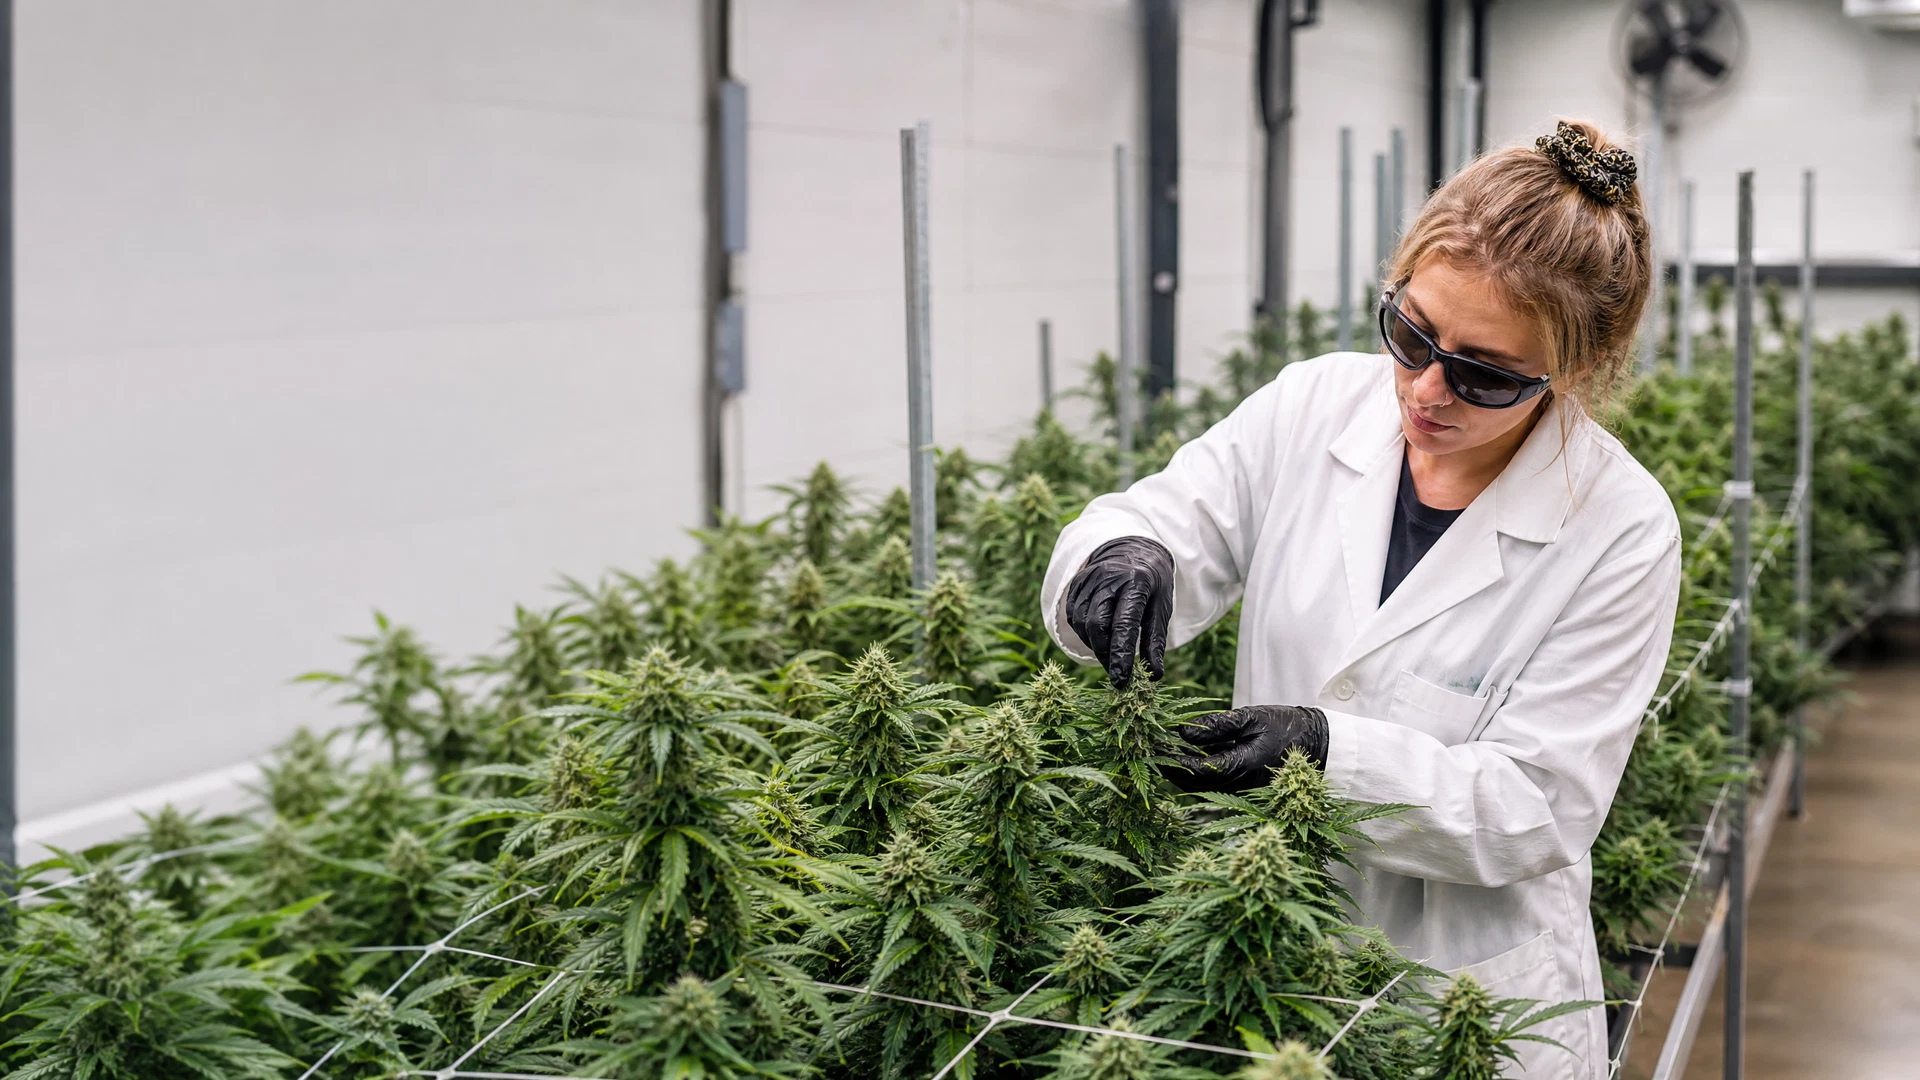
Licensed indoor, greenhouse, outdoor, nursery, and cultivation businesses managing plants, facilities, equipment, inventory, and staff.



Practical protection for licensed cultivation, retail, and cannabis operations.
Cannabis business insurance is a commercial insurance approach designed around licensed cultivation, retail, processing, manufacturing, distribution, delivery, inventory, security, regulated operations, equipment, customer premises, employees, and business property. Your operation may occupy a facility, manage products, use point-of-sale systems, transport inventory, or support regulated cannabis businesses.
Because regulated cannabis businesses combine valuable inventory, specialized equipment, employees, security, customer activity, data systems, product concerns, and evolving operating requirements, property, liability, crop or stock, workers compensation, cyber, crime, auto, and umbrella coverage discussions can be important. Coverage needs should reflect the activities and licensing of your actual operation.
Insure Pacific can help licensed cannabis businesses compare independent carrier options. We begin with your operations, facilities, inventory, security, staff, vehicles, agreements, systems, and regulatory obligations so the conversation fits your business.
A coverage review can be useful for licensed operations and service businesses managing cannabis products, property, employees, data, vehicles, or regulated facilities.
Licensed indoor, greenhouse, outdoor, nursery, and cultivation businesses managing plants, facilities, equipment, inventory, and staff.
Licensed retailers managing customer premises, product inventory, point-of-sale systems, security, deliveries, and regulatory requirements.
Licensed operations extracting, processing, manufacturing, packaging, testing, labeling, or producing cannabis products and related materials.
Businesses handling transport, storage, security, consulting, equipment, technology, and support services within the regulated cannabis supply chain.
The appropriate mix depends on your license, facilities, inventory, products, staff, security, vehicles, systems, agreements, and operations.
Review eligible facilities, grow rooms, retail space, improvements, equipment, inventory, contents, and business property.
Discuss covered third-party bodily injury, property damage, premises, operations, and product-related liability concerns subject to policy terms.
Review eligible plants, harvested product, inventory, raw materials, packaging, equipment, and valuation considerations.
Discuss coverage required for eligible employees and help address covered workplace injuries, subject to state requirements and policy terms.
Review eligible deliveries, transport vehicles, drivers, cargo, hired and non-owned auto, and business transportation exposures.
Consider coverage discussions for theft, employee dishonesty, money, securities, inventory, and security-related concerns.
Discuss protection for point-of-sale systems, payment data, customer records, seed-to-sale systems, software, and privacy-related events.
Review additional liability-limit and income-interruption discussions for eligible risks when greater limits or continuity planning are needed.
Annual policy review
Locations, licensing, inventory, product lines, equipment, staff, security, delivery, systems, and regulated operations can change your exposures. Review the details before renewal.
Common questions about protecting a licensed cannabis operation.
The conversation commonly includes property, general and product liability, crop or stock, workers compensation, auto, crime, cyber, income interruption, and umbrella coverage. The appropriate mix depends on your licensed activities and operations.
Coverage discussions may address eligible plants, harvested product, inventory, raw materials, packaging, equipment, and stock, subject to policy terms, valuations, security requirements, and carrier availability.
Cannabis operations can have significant inventory, cash, employee, customer, access, delivery, and security considerations. Crime and theft coverage may be an important discussion depending on your controls and operation.
Review before renewal and whenever licensing, locations, products, inventory, employees, security, vehicles, processing, delivery, systems, or material operations change.
Talk with an independent Insure Pacific agent about property, product liability, inventory, security, cyber, workers compensation, and commercial coverage considerations.
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


