



What Happens When a Key Piece of Equipment Breaks Down During Peak Season?
What Happens When a Key Piece of Equipment Breaks Down During Peak Season?

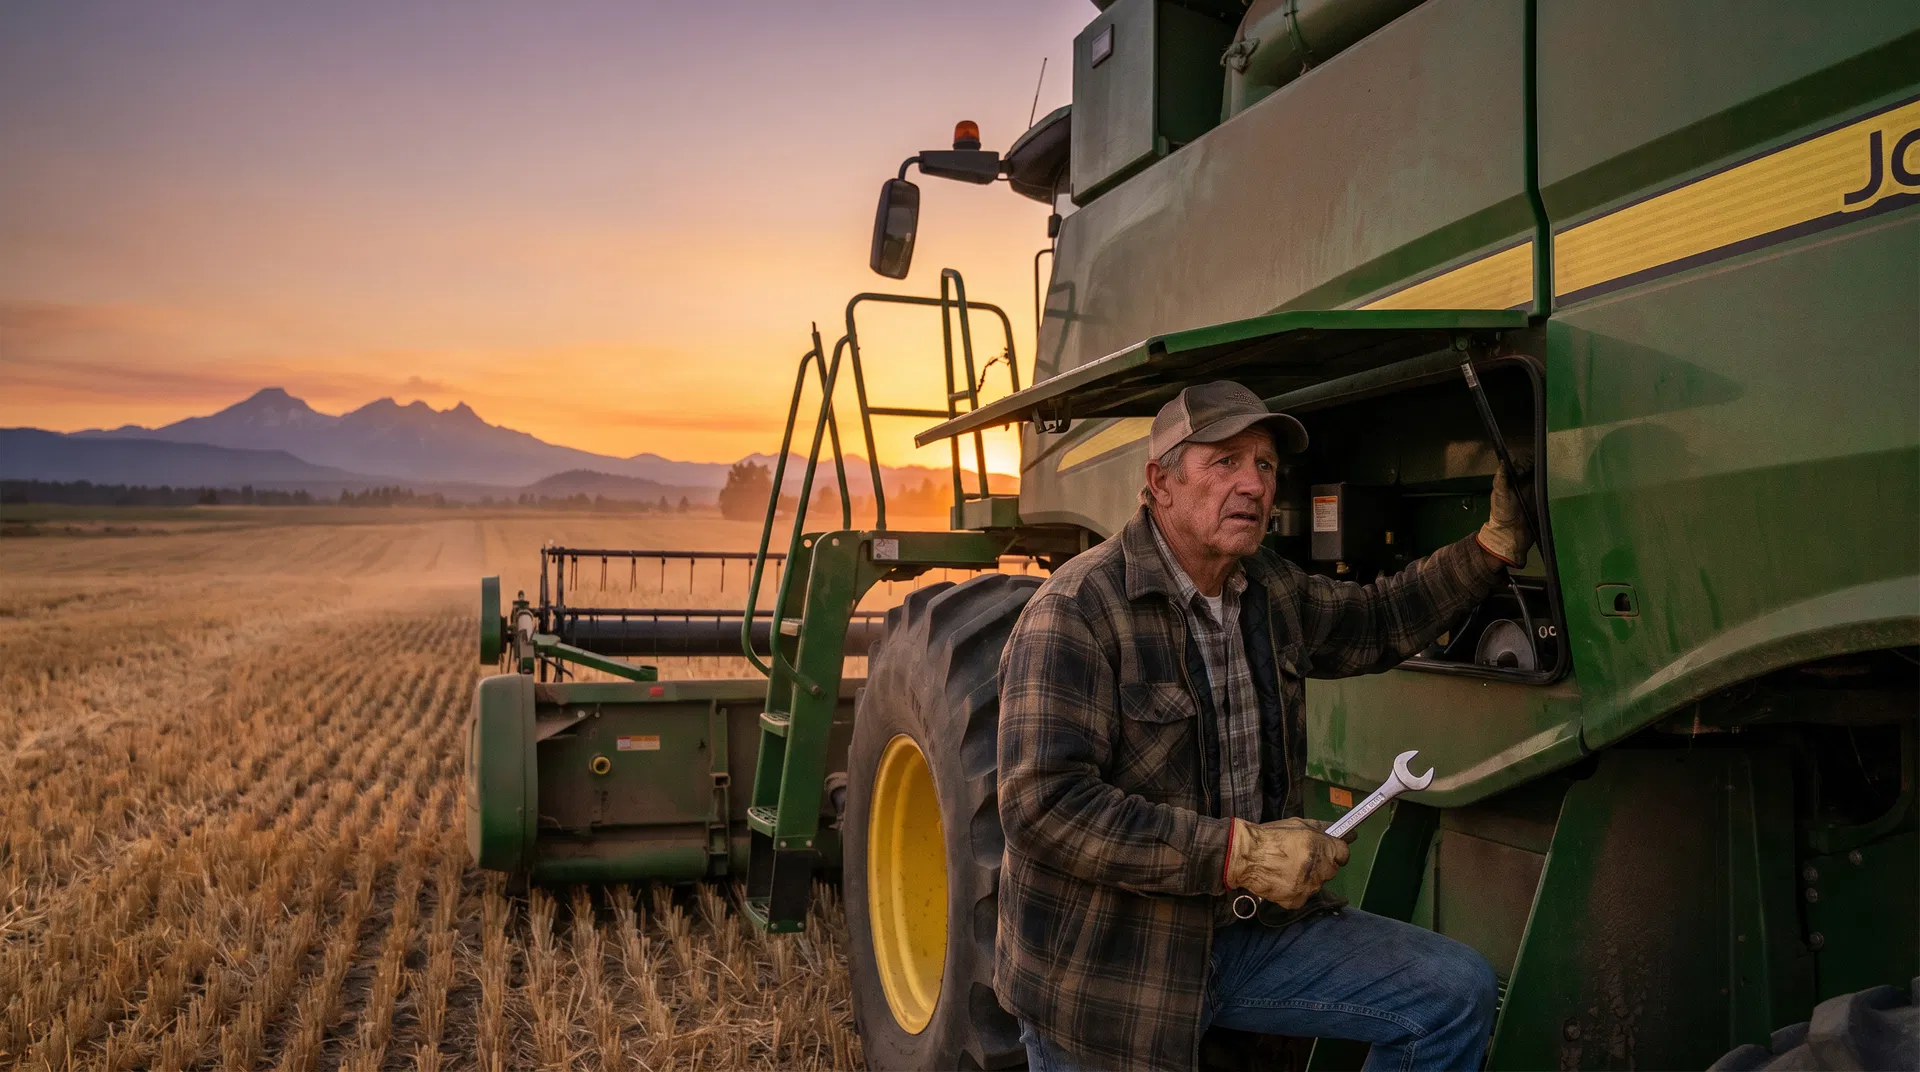
It always happens at the worst possible time. The irrigation pump fails on the hottest week of July. The combine breaks down with 200 acres still standing in the field. The manufacturing line goes down the week before a major delivery deadline. Equipment breakdown during peak season isn't just an inconvenience — it can mean the difference between a profitable year and a financial crisis. And the coverage most Oregon businesses rely on for protection — their standard commercial property policy — provides exactly zero dollars for mechanical or electrical breakdown.
Equipment breakdown insurance (also called boiler and machinery insurance) is one of the most underutilized and misunderstood coverages in commercial insurance. It fills the gap that standard property insurance leaves open: sudden and accidental mechanical, electrical, and pressure vessel failures. This guide covers the four situations where equipment breakdown coverage matters most for Oregon businesses — irrigation systems, manufacturing equipment, harvest machinery, and the broader category of business-critical equipment — and explains exactly what the coverage does and doesn't include.
The Coverage Gap Most Oregon Businesses Don't Know About
Standard commercial property insurance covers equipment damaged by fire, theft, wind, and other external perils — but explicitly excludes mechanical breakdown, electrical failure, and pressure vessel explosions. Equipment breakdown insurance is a separate policy (or endorsement) that covers exactly these excluded causes. Without it, a $75,000 irrigation pump failure or a $200,000 manufacturing equipment breakdown is entirely your expense.
Irrigation Pumps: When a Breakdown Means More Than Repair Costs
For Oregon farmers and ranchers, irrigation is not a convenience — it's a survival system. Central Oregon's high desert climate means that crops and livestock can face heat stress within 24 to 48 hours of losing water access during peak summer months. A failed irrigation pump during a July heat wave isn't just a repair problem; it's a potential crop loss event that can dwarf the cost of the pump itself.
Equipment breakdown coverage for irrigation systems typically includes the repair or replacement of the pump motor, controller, and associated electrical components when they fail due to mechanical breakdown, electrical arcing, or motor burnout. Critically, it also covers the consequential losses that result from the breakdown — including spoiled crops, livestock losses, and the cost of renting temporary pumping equipment while the primary system is repaired.
The most common causes of irrigation pump failures in Oregon are motor burnout from running dry (when water levels drop unexpectedly), electrical surge damage from lightning strikes, and bearing failures from deferred maintenance. Of these, running dry and electrical surge are typically covered under equipment breakdown policies; bearing failures from gradual wear may be excluded as "wear and tear." Understanding these distinctions before you file a claim — not after — is essential.
What Equipment Breakdown Covers for Irrigation Systems
Covered: Motor burnout, electrical arcing, mechanical failure, surge damage, pump impeller failure
Covered (consequential): Crop losses, livestock losses, temporary rental equipment, expediting expenses
Typically excluded: Gradual wear and tear, corrosion, improper maintenance, flood or drought damage
Key limit to check: Consequential loss sublimit — ensure it's adequate for your crop value
Oregon farmers should review their equipment breakdown coverage limits annually, particularly as crop values change. A consequential loss sublimit of $25,000 that was adequate five years ago may be insufficient for today's crop values. Our farm and ranch insurance specialists can review your current coverage and identify gaps before peak season.
Manufacturing Equipment: The Hidden Cost of Unplanned Downtime
For Oregon manufacturers, equipment breakdown during peak production periods can be catastrophic. The direct cost of repairing or replacing failed equipment is often the smaller part of the total loss — the larger cost is the business interruption: lost production, missed delivery deadlines, expedited freight costs, customer penalties, and the long-term damage to customer relationships.
Equipment breakdown insurance for manufacturers covers the repair or replacement of production equipment, boilers, pressure vessels, refrigeration systems, and electrical distribution equipment when they fail due to sudden and accidental mechanical or electrical causes. The business interruption component — often called "extra expense" or "business income" coverage — pays for the additional costs of maintaining operations during the repair period, including overtime labor, temporary equipment rental, and outsourcing production to third parties.
Oregon manufacturers who operate specialized or custom equipment face a particular challenge: replacement parts may have long lead times, and in some cases, the equipment itself may need to be rebuilt or custom-fabricated. Equipment breakdown policies can include "expediting expense" coverage that pays for premium freight, overtime labor, and other costs to accelerate the repair process — often the most valuable component of the coverage for manufacturers with tight production schedules.
| Equipment Type | Common Failure Modes | Typical Claim Range |
|---|---|---|
| CNC Machining Centers | Spindle failure, controller board failure, coolant system failure | $15,000–$150,000+ |
| Boilers & Pressure Vessels | Tube failure, control failure, explosion | $25,000–$500,000+ |
| Refrigeration Systems | Compressor failure, refrigerant leak, condenser failure | $10,000–$75,000 |
| Electrical Transformers | Insulation failure, overload, lightning surge | $20,000–$200,000 |
| Conveyor Systems | Motor failure, gearbox failure, belt failure | $5,000–$50,000 |
| Air Compressors | Motor failure, valve failure, tank failure | $3,000–$30,000 |
Oregon manufacturers should also consider whether their equipment breakdown policy includes coverage for data restoration — increasingly important as manufacturing equipment becomes more computerized. A CNC machine that loses its programming due to a controller failure may require significant time and expense to reprogram, and this cost is often not covered under standard equipment breakdown policies without a specific data restoration endorsement. Learn more about our commercial insurance programs for Oregon manufacturers.
Harvest Machinery: When the Window Is Measured in Days, Not Weeks
Oregon's diverse agricultural landscape — from the grass seed fields of the Willamette Valley to the wheat farms of eastern Oregon to the orchards of Hood River — means that harvest timing is critical. Many crops have narrow harvest windows where weather, moisture content, and market conditions all align. A combine, harvester, or processing equipment failure during this window can mean the difference between a successful harvest and a total crop loss.
Farm equipment breakdown coverage differs from standard farm property insurance in an important way: it covers the mechanical failure of the equipment itself, not just damage from external causes. A combine that throws a rod or a harvester that suffers a hydraulic system failure is covered under equipment breakdown — not under the farm property policy that covers the same combine if it's damaged in a fire or collision.
The most valuable component of harvest equipment breakdown coverage is often the "expediting expense" provision, which pays for emergency repairs, parts air freight, and even the cost of renting replacement equipment to keep the harvest moving. In Oregon's competitive harvest equipment rental market, finding available replacement equipment during peak season can be extremely difficult — and expensive. Having coverage that pays for these emergency costs can save a harvest that would otherwise be lost.
Combines & Harvesters
Threshing cylinder failures, header drive failures, and grain elevator chain failures are the most common claims. Repair costs of $20,000–$80,000 are not unusual for modern combines.
Irrigation Pivots
Center pivot drive failures, tower motor failures, and control panel failures can leave hundreds of acres without water. Coverage includes both repair costs and consequential crop losses.
Grain Handling Equipment
Auger failures, elevator leg failures, and dryer burner failures during harvest can create significant bottlenecks. Equipment breakdown covers repair costs and business interruption.
Processing Equipment
For Oregon's specialty crop producers — hops, hazelnuts, mint — processing equipment failures during harvest can be catastrophic. Coverage should match the full value of the crop at risk.
Oregon farmers should review their equipment breakdown coverage before each harvest season — not after a failure occurs. Coverage limits, deductibles, and consequential loss sublimits should be reviewed annually as equipment values and crop values change. Our farm and ranch insurance team specializes in agricultural equipment coverage for Oregon's diverse farming operations.
How Equipment Breakdown Insurance Actually Works
Equipment breakdown insurance is triggered by a "breakdown" — defined as a sudden and accidental physical damage to covered equipment that requires repair or replacement. The coverage pays for the cost to repair or replace the damaged equipment, plus additional coverages that vary by policy: business interruption, extra expense, spoilage, expediting expense, and data restoration.
Most equipment breakdown policies are written on an "all equipment" basis, covering virtually every piece of mechanical, electrical, and pressure equipment on your premises. This is more efficient than trying to schedule individual pieces of equipment, and it ensures that you don't discover a coverage gap when a piece of equipment you didn't think to list fails during peak season.
The deductible structure for equipment breakdown is typically either a flat dollar amount (e.g., $1,000 or $5,000 per breakdown) or a time-element deductible for business interruption (e.g., 8 hours or 24 hours). Choosing the right deductible requires balancing premium cost against your ability to absorb smaller losses — and your tolerance for the administrative burden of filing small claims.
Report the Breakdown Immediately
Most equipment breakdown policies require prompt notice of a breakdown. Delaying notification can jeopardize your claim. Call your agent as soon as a covered breakdown occurs.
Don't Discard Damaged Parts
The insurance company will want to inspect the failed equipment to determine the cause of loss. Preserve all damaged parts until the adjuster has completed their inspection.
Document Your Losses
Keep records of all repair costs, rental equipment costs, overtime labor, spoiled inventory, and lost production. These records are essential for maximizing your claim recovery.
Understand Your Policy's Consequential Loss Provisions
The consequential loss coverage — for crop losses, spoiled inventory, or lost production — often has sublimits that are separate from the equipment repair limit. Know these limits before you need them.
Review Coverage Annually
Equipment values change, crop values change, and your operations change. Review your equipment breakdown coverage every year to ensure limits are adequate and all covered equipment is included.
Equipment breakdown insurance is one of the most cost-effective coverages available for Oregon farms, manufacturers, and businesses that depend on mechanical equipment. The premium is typically modest relative to the potential loss — and the peace of mind of knowing that a peak-season breakdown won't become a financial catastrophe is invaluable. To review your current coverage or add equipment breakdown protection, get a free quote or contact our team. You may also want to explore our guides on farm and ranch insurance and commercial insurance for Oregon businesses.
Our Licensed Coverage Area
States highlighted in blue are states where Insure Pacific holds an active insurance license.
Hover to highlight — click a state to visit its insurance page
Our Oregon Office Locations
Hover over a marker to see the office — click to visit their website.
Hover to highlight — click to visit that office's website
Ready to Get Protected?
Talk to a Local Oregon Insurance Expert
Insure Pacific has been serving Oregon families and businesses since 1935. We work with 50+ carriers so you get real options — not just one company's answer.
Related Articles
 Commercial Insurance
General Liability Insurance: What It Covers—and What It Doesn’t
Read Article → Commercial Insurance
Multi-State Workers’ Compensation: Remote Employees, Traveling Crews, and Out-of-State Jobs
Read Article → Commercial Insurance
Import and Export Cargo Insurance: Ocean Freight, Ports, Customs, and Inland Transportation
Read Article → Commercial Insurance
Has Your Business Outgrown Its Insurance? Revenue, Payroll, New Locations, and New Services
Read Article →Get in Touch
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


