



Landlord, Short-Term Rental & Commercial Property Insurance: Vacancy, Liability, Loss of Rents, Wildfire & Water Damage
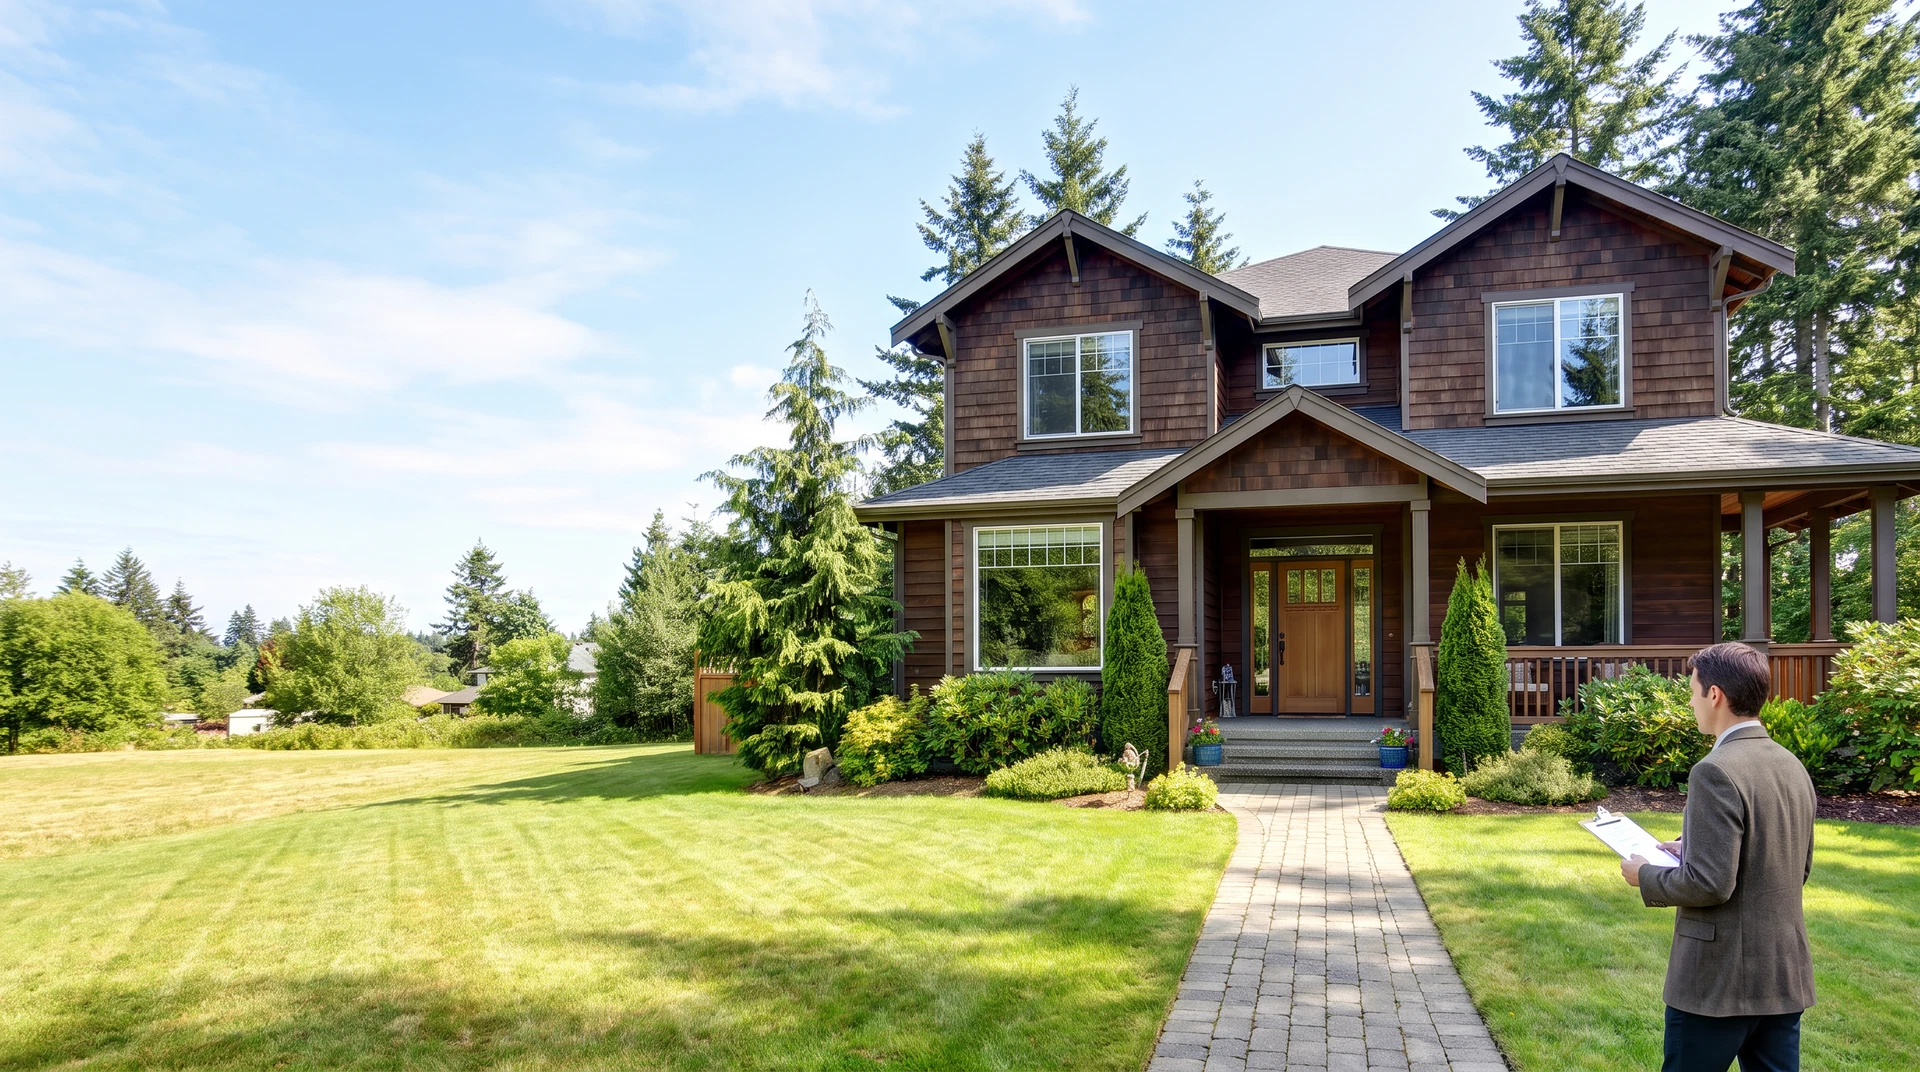
Landlord, Short-Term Rental & Commercial Property Insurance: Vacancy, Liability, Loss of Rents, Wildfire & Water Damage

A property can change its insurance profile faster than its owner expects. A long-term rental may become a furnished monthly stay. A vacation home may begin accepting weekend guests. A retail-and-office building may gain a new tenant, remodel a suite, sit empty between leases, or sustain a water loss that disrupts rent collections. Each change deserves a deliberate coverage conversation rather than an assumption that a prior homeowners or property policy will follow the new use.
This guide is designed for landlords, short-term rental hosts, real-estate investors, and owners of small commercial buildings across Oregon and Insure Pacific’s Western-state service area. It explains the questions to raise before a renewal, lease change, vacancy, renovation, severe-weather event, or booking season. It is educational rather than policy language; actual coverage depends on the carrier, endorsements, limits, exclusions, property condition, location, and completed application.
Start with the property’s actual use
The first underwriting question is not simply “Is this a house?” or “Is this a commercial building?” It is how the property is used today. A year-long residential lease, a furnished rental, a home shared with an owner, a vacation rental, a mixed-use building, a vacant property, and a property under renovation can call for different coverage forms, disclosures, or underwriting approvals.
For long-term residential rentals, begin with a review of Landlord Insurance and current lease terms. For a home rented for stays shorter than a traditional lease, ask directly whether the policy is written to contemplate short-term rental activity. Platform protections, cancellation policies, deposits, and house rules may be useful operational tools, but they are not a substitute for reading the insurance policy and confirming the scheduled use with the carrier.
For a retail, office, warehouse, or mixed-use location, begin with Business Property Insurance. The discussion should identify building ownership, tenants, construction type, roof age, fire protection, square footage, occupancy, leased equipment, tenant improvements, and whether the owner also operates a business from the premises.
Vacancy and unoccupied-property questions are not interchangeable
An empty unit can be part of normal ownership, but it still needs to be described accurately. Insurers may distinguish between a temporarily unoccupied property, a vacant unit with no contents or regular activity, a building between tenants, and a property undergoing a substantial renovation. Policy conditions and eligibility can change after a stated period of vacancy, and some losses—especially water, vandalism, theft, or glass damage—may receive different treatment.
Create a vacancy file before the property is empty. Record the date the tenant left, utilities and heat status, inspection schedule, property-manager contacts, winterization steps, security measures, planned repairs, photos, and any new marketing or construction activity. Ask whether the carrier requires notice, an endorsement, or a vacant-building policy. Do not wait until a frozen pipe, break-in, or storm claim to discover that the period of vacancy mattered.
Premises liability follows the people and conditions you invite onto the property
Owners can face liability questions when tenants, guests, vendors, delivery drivers, contractors, or visitors allege injury or property damage. Common concerns include wet walkways, stairs and railings, parking lots, decks, pools or hot tubs, snow and ice, uneven surfaces, handrails, lighting, dog exposures, code maintenance, and work performed by contractors. A short-term rental introduces more frequent turnover and may involve guests unfamiliar with the property, local conditions, parking, fireplaces, decks, or emergency procedures.
Maintain a documented maintenance rhythm. Use seasonal inspections, repair logs, vendor agreements, incident records, and clear emergency-contact procedures. Review General Liability Insurance for commercial-property operations and discuss how a personal or landlord liability limit interacts with the ownership structure, management agreement, and umbrella strategy. Owners with significant assets should also ask whether Personal Umbrella Insurance or Commercial Umbrella Insurance is appropriate.
Loss of rents and business-income questions need a realistic numbers review
The physical repair is not the only financial consequence of a covered property loss. If a rental unit cannot be occupied because of covered damage, an owner may lose scheduled rental income while mortgage payments, taxes, utilities, payroll, and repair decisions continue. Depending on the policy and situation, landlords may have loss-of-rents protection and commercial owners may have business-income and extra-expense coverage. The details matter: waiting periods, restoration periods, conditions, sublimits, deductibles, and the definition of covered cause of loss can all affect the result.
Keep a simple rent-and-expense record for every property: lease schedule, historical rent, seasonality for short-term rentals, deposits, tenant ledger, fixed expenses, tax records, lender statements, and a current forecast. For commercial buildings, separately identify owner rental income, tenants’ operating income, common-area expenses, and any business conducted by the owner. The NFIP’s commercial coverage overview specifically notes that its flood policies do not cover business interruption or loss of use, reinforcing why flood and income-protection questions must be reviewed separately.1
Water damage: separate sudden events from maintenance and water entering from outside
“Water damage” is not one coverage question. A burst interior pipe, appliance leak, roof leak, seepage over time, sewer or drain backup, surface-water flood, mold, and groundwater can be treated differently under a policy. Review the property’s plumbing age, supply lines, water heaters, roof, drainage, sump equipment, foundation, shutoff access, and freeze-protection plan. For short-term rentals, add a guest-ready shutoff instruction, leak sensors where practical, emergency vendor contact, and a manager response plan.
Ask the agent to identify what the policy says about water backup, what endorsement options may be available, how deductibles work, and how renovation activity is treated. Avoid relying on a generic phrase such as “water is covered.” The right conversation distinguishes the cause of loss, the affected property, preventative maintenance expectations, and the limit available to restore the building, furnishings, and income stream.
Flood deserves its own decision, not an assumption
FEMA explains that flood insurance is separate from most homeowners insurance and is available to property owners, renters, and businesses.2 Flood can involve rising water, runoff, and other conditions that are not the same as a pipe leak. A property outside a high-risk map zone can still have exposure, so owners should consider location, drainage, elevation, nearby waterways, prior water history, lower-level improvements, tenant contents, and lender requirements.
For commercial risks, the NFIP describes separate commercial building and commercial personal-property coverage, with stated limits up to $500,000 for each type of policy.1 Whether those limits, valuation rules, exclusions, waiting periods, or available private-market alternatives fit a particular building requires a property-specific review. Do not wait for a forecast or a closing deadline: FEMA says an NFIP policy typically has a 30-day waiting period, subject to stated exceptions.2
Wildfire readiness should combine insurance and property operations
Wildfire underwriting is not just a rural-property concern. Owners should understand the building’s location, construction, defensible-space conditions, access, roof and vent condition, vegetation, outbuildings, occupancy, emergency plans, and ability to document maintenance. A vacant property can be particularly challenging if an owner cannot arrange inspections, remove combustible debris, or respond promptly to a smoke, ember, or water-intrusion event.
Review the property with the same practical discipline used for Wildfire Insurance: keep addresses and contacts current, preserve maintenance records, understand inspection requests, communicate material improvements, and never represent occupancy or use inaccurately. Owners should also consider their own cash-flow continuity if a tenant or guest cancels, an access route closes, or repairs are delayed by regional demand.
Short-term rentals add compliance and operations to the insurance conversation
Short-term rental rules are local and can change. In Bend, a short-term rental is defined as a house, apartment, or room rented for fewer than 30 consecutive days per guest; the city publishes licensing, permit, emergency-contact, safety-checklist, room-tax, renewal, and good-neighbor requirements.3 The property’s local rules, HOA or condominium documents, lender requirements, and management agreement should be part of the ownership file.
Maintain a written operating plan that includes guest screening practices, parking instructions, occupancy limits, emergency contacts, property rules, smoke and carbon-monoxide alarms, fire-extinguisher checks, pool or hot-tub controls if applicable, housekeeper and vendor agreements, and incident reporting. Discuss whether the policy responds to furnished contents, guest-caused damage, amenities, alleged injury, liquor exposure, hired services, loss of booking income, or a change from occasional rental use to a regular business activity.
Commercial-property owners must coordinate leases, tenants, and building systems
Commercial insurance cannot be reviewed in isolation from the lease. A lease may define who insures the building, tenant improvements, contents, glass, signage, utility service, indemnity obligations, additional-insured requirements, waiver provisions, and responsibility for snow removal or repairs. The owner should not rely on a certificate alone to understand the relationship; retain the lease, verify the named insured, obtain certificates when appropriate, and review changes with qualified legal and insurance advisers.
Building systems also deserve attention. Electrical, plumbing, heating, cooling, fire suppression, alarm, elevator, refrigeration, and security systems can create direct damage and prolonged downtime risks. Depending on the operation, a review may include Equipment Breakdown Insurance, ordinance or law coverage, service-line questions, and cyber safeguards for building-access, payment, security, or property-management systems.
Building valuation, coinsurance, and ordinance or law deserve plain-English questions
The building limit is not a market-value estimate. It is generally intended to support repair or reconstruction under the form of valuation described in the policy. Land value, desirability, rental income, and the price paid for a building do not necessarily match the cost to rebuild after a substantial fire or wind loss. Owners should review the property’s construction, square footage, finishes, roof, attached and detached structures, accessibility features, mechanical systems, and local rebuilding requirements before renewal.
Ask how the insurer calculates building value, whether the policy includes replacement cost or another valuation basis, and whether a coinsurance condition applies. Ordinance or law coverage is a separate question: after a covered loss, a building may need to be demolished, rebuilt, or upgraded to comply with codes that did not apply when it was originally constructed. A commercial landlord should also confirm how tenant improvements and betterments are allocated between owner and tenant. The answer is often found in both the lease and the policies—not in the certificate alone.
Separate the building, the owner’s contents, and the tenant’s property
An owner may hold a building policy while tenants insure their own inventory, furniture, equipment, signs, stock, or improvements. That arrangement only works when the boundaries are documented. Residential landlords can require renters insurance where permitted and reasonable, while commercial landlords commonly use lease insurance clauses and certificates to document agreed requirements. However, a certificate is not the policy itself; it should be treated as evidence to review, not a substitute for reading the lease and obtaining professional advice.
Short-term rental hosts should inventory host-owned furnishings, appliances, linens, outdoor equipment, electronics, and specialty amenities. Commercial owners should separately list building-owned contents such as maintenance equipment, common-area furnishings, security systems, leasing-office property, and emergency supplies. For portable maintenance equipment or property that moves between sites, ask whether Inland Marine Insurance is relevant.
Independent Insurance Agency Since 1935
Not Sure If You Have the Right Coverage?
Our licensed agents compare 50+ carriers to find you the best coverage at the right price — at no extra cost to you.
Renovation, remodeling, and tenant turnover can change the insurance answer
Painting a unit between occupants is different from opening walls, relocating plumbing, replacing a roof, or converting office space into a new occupancy. Construction, vacancy, hot work, utility shutoffs, scaffolding, demolition, and unsecured openings can all alter a property’s exposure. Before work begins, discuss the scope, estimated cost, contractors, subcontractors, jobsite security, delivery storage, construction timetable, and whether the property will remain occupied.
Depending on the project, an owner may need to explore Builders Risk Insurance, contractor insurance requirements, an installation or renovation endorsement, or a separate vacant-building solution. Obtain written contracts, confirm the responsible parties, and ask contractors for their insurance documentation. Do not assume the owner’s building policy automatically covers every contractor-caused loss, every theft of materials, or every delay.
Ownership structure affects how the policy should be written
Many properties are owned through an LLC, partnership, trust, family entity, or a combination of entities. Property managers, members, managers, trustees, lenders, spouses, and operating businesses may all have an interest that needs to be reviewed. A mismatch between the deed, loan documents, lease, and policy named insured can complicate a claim or renewal.
Bring the current declarations, entity name, ownership schedule, management agreement, and lender requirements to the review. The objective is not to add every interested party indiscriminately; it is to ensure the application accurately reflects ownership, operations, and contractual relationships. If a property-management firm is hired, examine responsibility for inspections, emergency response, tenant screening, vendor oversight, rent collection, incident reporting, and insurance notices.
Hired vendors, employees, and vehicle activity create their own exposures
Even a small owner-operated portfolio may involve cleaners, landscapers, snow-removal providers, handypersons, plumbers, electricians, restoration firms, security vendors, or temporary employees. A property owner needs to know who hires them, which contracts apply, who supervises the work, what insurance they carry, and how a claim is reported. Commercial owners who employ maintenance staff should also review Workers’ Compensation Insurance and payroll classifications.
Vehicle exposure can be overlooked when an owner, manager, or employee uses a personal vehicle for property errands, supply runs, inspections, or guest support. Where business use is material, review Commercial Auto Insurance and hired/non-owned auto questions. A personal auto policy, employer relationship, and commercial entity need to be evaluated together rather than one at a time.
Claims preparation begins before a loss
After a fire, severe water event, guest injury, vandalism, or tenant-displacement event, records are more useful when they are already organized. Keep an offsite or cloud-backed property file with current photographs and video, repair invoices, maintenance records, inspections, lease schedules, tenant and guest communications, vendor contracts, emergency contacts, bank details for rent deposits, and a contents inventory. Preserve damage, take reasonable steps to protect the property from further loss when safe, and report a potential claim promptly under the policy’s notice requirements.
The goal is not to decide coverage without the insurer. It is to help the insurer and adjuster understand what happened, what was damaged, who was affected, what income was interrupted, and what practical steps are necessary to stabilize the property. In a major event, careful documentation can also support conversations with lenders, tenants, contractors, and local authorities.
Portfolio owners should review concentration and shared risk
An owner with multiple rentals or commercial locations should look beyond each building in isolation. Are several properties in the same wildfire area, flood-prone corridor, utility service zone, or weather pattern? Do several units rely on one property manager, one booking platform, one maintenance vendor, or one common access road? A portfolio may benefit from a discussion of scheduling, blanket versus location-specific limits, deductibles, entity structure, catastrophe planning, and the limits of any umbrella policy.
This is also where a single calendar helps. Schedule renewal reviews, roof inspections, water-heater replacement decisions, tree and vegetation work, lease expirations, permit renewals, lender notices, and seasonal wildfire or freeze preparation. Insurance cannot eliminate operational risk, but a documented calendar can reduce last-minute decisions and make the next coverage conversation much more productive.
A renewal checklist for owners and managers
| Review area | Owner questions to document |
|---|---|
| Use and occupancy | Is the property long-term rental, short-term rental, owner occupied, commercial, mixed use, vacant, or under renovation? |
| Building value | Do limits reflect current reconstruction costs, tenant improvements, code requirements, and detached structures? |
| Income | Is loss-of-rents or business-income information current, including seasonal booking revenue and continuing expenses? |
| Water and flood | What causes of water loss are covered, and should sewer-backup or separate flood coverage be evaluated? |
| Liability | Are leases, vendors, amenities, maintenance responsibilities, and umbrella limits aligned with the ownership structure? |
| Wildfire and continuity | Are mitigation records, contacts, inspections, evacuation plans, and interruption planning current? |
Questions to bring to an insurance review
| If you own… | Ask these practical questions |
|---|---|
| A long-term rental | Is the dwelling, liability, loss-of-rents, water-backup, and vacancy structure still consistent with the lease and current condition? |
| A short-term rental | Has the frequency of bookings, furnished contents, amenities, local permit status, property manager, and guest use been disclosed? |
| A commercial building | Are building valuation, tenant improvements, lease requirements, business income, ordinance or law, equipment breakdown, and flood questions documented? |
| A mixed-use property | Are the residential and commercial operations accurately described, and are the occupancy, exits, systems, and contractual arrangements aligned? |
| A growing portfolio | Are each location, entity, management relationship, deductible, catastrophe concentration, and umbrella limit being reviewed together? |
The most useful next step: review before the next change
An insurance review is most valuable before a tenant moves out, a property is advertised for short-term stays, a commercial lease is signed, a renovation begins, a building sits empty, or a weather season arrives. Bring the current declarations, lease or management agreement, valuation information, rent schedule, renovation scope, loss history, inspection notices, and any carrier correspondence. That preparation helps an agent identify questions early rather than after a claim.
For a landlord, vacation rental, or commercial-property review, request a quote, call Insure Pacific at (541) 238-7775, or send a message. We can help organize the questions, compare appropriate options from multiple carriers, and coordinate a review around the way the property is actually used.
References
[1] FEMA / NFIP — The Ins and Outs of NFIP Commercial Coverage
Our Licensed Coverage Area
States highlighted in blue are states where Insure Pacific holds an active insurance license.
Hover to highlight — click a state to visit its insurance page
Our Oregon Office Locations
Hover over a marker to see the office — click to visit their website.
Hover to highlight — click to visit that office's website
Ready to Get Protected?
Talk to a Local Oregon Insurance Expert
Insure Pacific has been serving Oregon families and businesses since 1935. We work with 50+ carriers so you get real options — not just one company's answer.
Related Articles
 Commercial Insurance
General Liability Insurance: What It Covers—and What It Doesn’t
Read Article → Commercial Insurance
Multi-State Workers’ Compensation: Remote Employees, Traveling Crews, and Out-of-State Jobs
Read Article → Commercial Insurance
Import and Export Cargo Insurance: Ocean Freight, Ports, Customs, and Inland Transportation
Read Article → Commercial Insurance
Has Your Business Outgrown Its Insurance? Revenue, Payroll, New Locations, and New Services
Read Article →Get in Touch
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


