



Nonprofit Insurance in Oregon and the American West: The Complete 2026 Guide
Nonprofit Insurance in Oregon and the American West: The Complete 2026 Guide

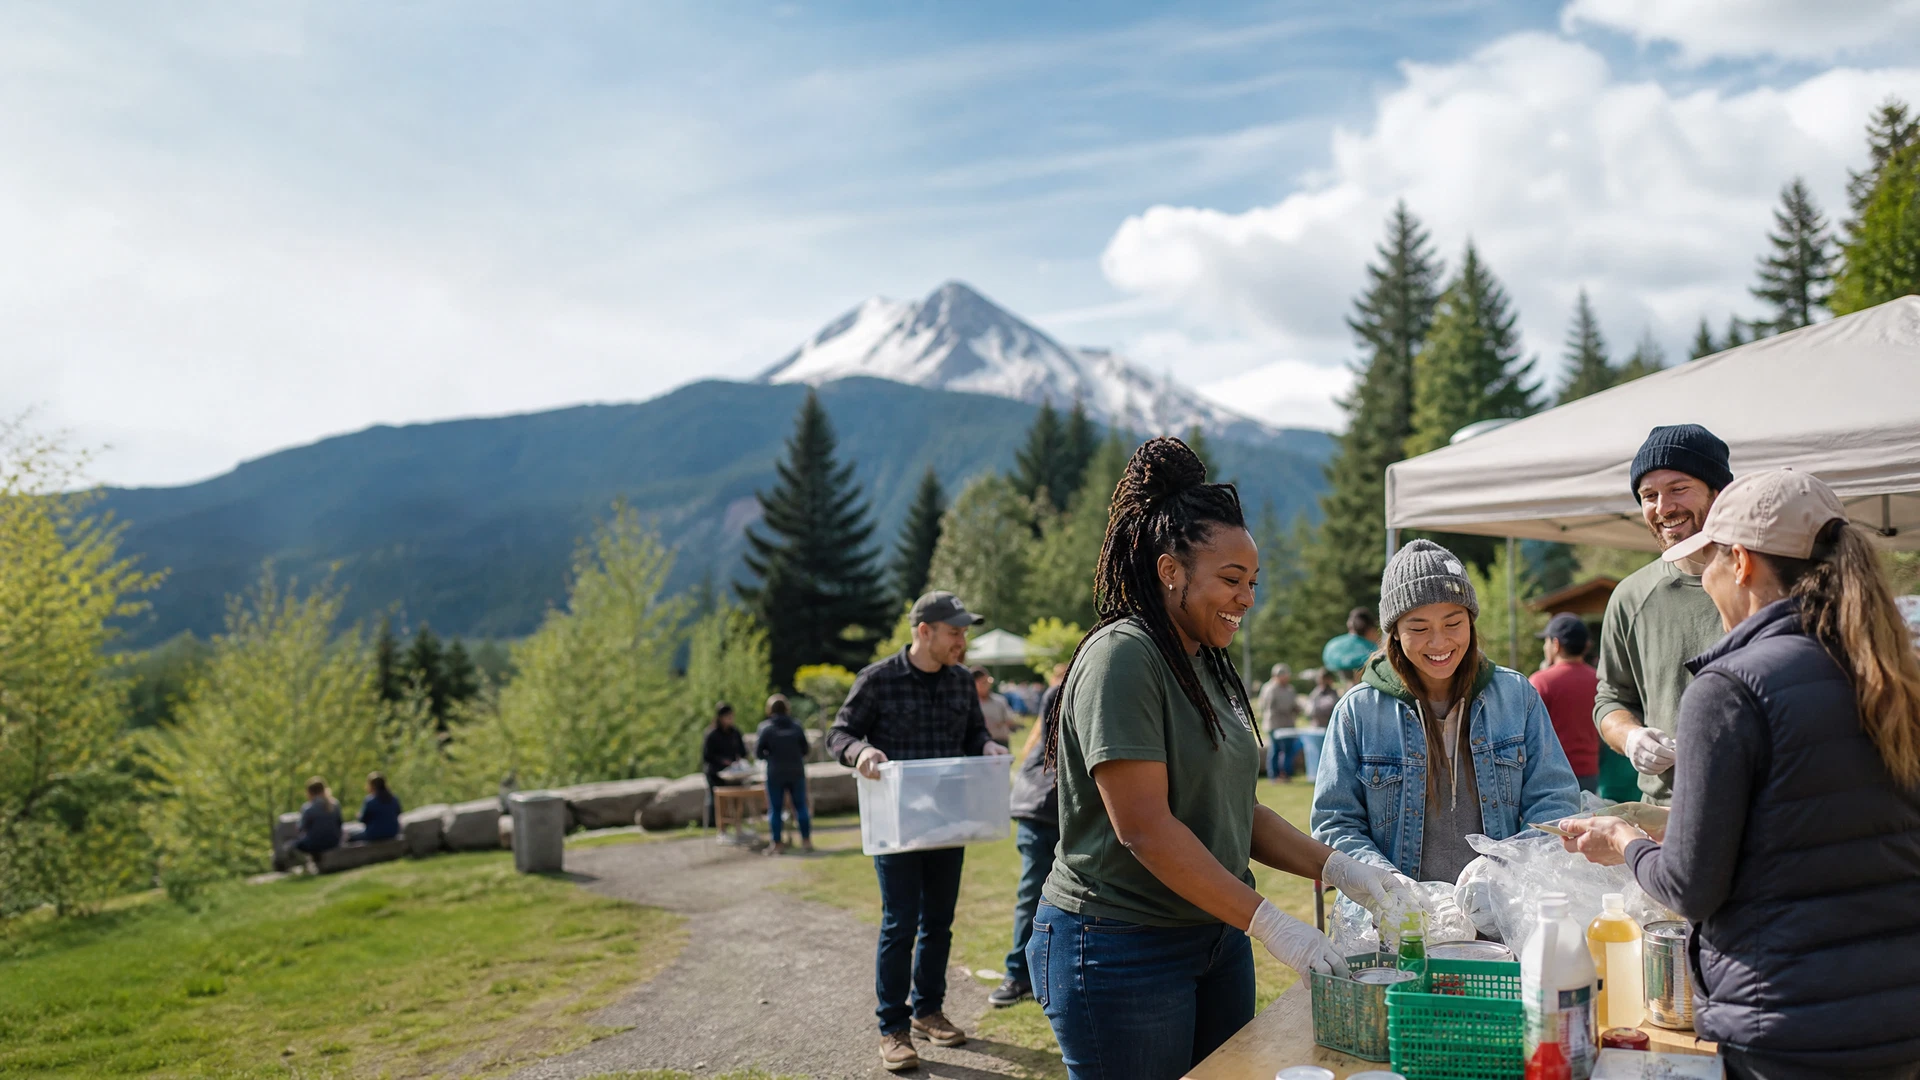
Oregon is home to more than 21,500 registered charitable nonprofits — from youth sports leagues in Prineville to food banks in Bend, arts organizations in Ashland to faith communities in Sisters. Across the American West, nonprofits are the connective tissue of communities, running on passion, volunteerism, and tight budgets. And they are, far too often, dangerously underinsured.
A single lawsuit from a board member dispute, a volunteer injury at a fundraising event, or a data breach exposing donor information can cost a nonprofit tens of thousands of dollars — and in some cases, force it to close entirely. Yet many nonprofit leaders assume that their tax-exempt status, their good intentions, or a basic general liability policy provides adequate protection. It does not.
This guide covers everything Oregon and American West nonprofit leaders, board members, and executive directors need to know about nonprofit insurance in 2026 — the coverages you need, the risks you face, what it costs, and how an independent insurance agent can help you build a comprehensive protection program without breaking your budget.
Why Nonprofits Face Unique Insurance Risks
Nonprofits are not simply small businesses with a different tax status. They operate in ways that create specific liability exposures that standard commercial insurance policies are not designed to address. Three risks stand out as particularly significant for Oregon and American West nonprofits.
Volunteer liability is one of the most significant and most overlooked risks. When a volunteer is injured while working for your organization, or when a volunteer causes injury to a third party, your nonprofit can be held responsible. Oregon's volunteer protection statutes under ORS 30.462 provide some immunity for individual volunteers, but they do not eliminate liability for the organization itself — particularly when the nonprofit is found to have been negligent in supervising or training volunteers.
Board member personal exposure is another critical concern. Directors and officers of Oregon nonprofits — including unpaid board volunteers — can be personally sued for decisions made on behalf of the organization. Claims of mismanagement, breach of fiduciary duty, misuse of grant funds, failure to follow bylaws, and employment-related decisions are all common triggers for Directors & Officers (D&O) claims. Without D&O insurance, a board member's personal assets — their home, savings, and retirement accounts — are at risk.
Special event exposure is a third area where nonprofits are frequently caught off guard. Fundraising galas, community festivals, 5K runs, and holiday markets all create temporary but significant liability exposure. Standard general liability policies may exclude or limit coverage for special events, particularly those involving alcohol service, amusement rides, or large crowds. Oregon's Dram Shop Act creates strict liability for organizations that serve alcohol to guests who later cause harm.
Is Your Nonprofit Properly Protected?
Many Oregon nonprofits are operating with significant coverage gaps — no D&O, inadequate event coverage, or volunteers excluded from their policy. Insure Pacific works with specialty nonprofit carriers to build comprehensive protection programs for organizations of all sizes.
The Seven Core Coverages Every Oregon Nonprofit Should Have
1. General Liability Insurance
General liability is the foundation of any nonprofit insurance program. It covers bodily injury and property damage claims arising from your operations, events, and premises — the slip-and-fall at your annual gala, the property damage caused by a volunteer, the injury at your youth program. For any nonprofit that hosts events, operates a facility, or has volunteers interacting with the public, general liability is non-negotiable.
For Oregon nonprofits, general liability premiums typically range from $400–$900 per year for small organizations with revenues under $500,000, and $900–$2,500 per year for mid-size organizations with revenues between $500,000 and $2 million. Most venue contracts and grant agreements require proof of general liability coverage before your organization can operate.
2. Directors & Officers (D&O) Insurance
D&O insurance is the most important coverage that Oregon nonprofits consistently overlook. Many board members assume that because they are volunteers — not paid executives — they cannot be personally sued. This is a dangerous misconception.
Oregon law does provide some limited immunity for volunteer directors under ORS 65.369, but this protection is narrow. It does not apply when the director was grossly negligent, acted outside the scope of their duties, received compensation for the act in question, or when the claim involves employment-related decisions. In practice, the most common D&O claims against nonprofits — employment disputes, financial mismanagement allegations, and grant fund misuse — fall squarely outside the scope of Oregon's volunteer immunity statute.
A well-structured D&O policy typically includes three components: Side A coverage (protecting individual board members when the organization cannot indemnify them), Side B coverage (reimbursing the organization when it indemnifies a board member), and Employment Practices Liability (EPL) coverage for claims arising from hiring, firing, discrimination, and harassment decisions. For small nonprofits with annual revenues under $1 million, a basic D&O policy with $1 million in limits typically costs $800–$2,500 per year — a modest investment compared to the cost of defending even a frivolous lawsuit, which can easily exceed $50,000 in legal fees before a case ever reaches trial.
3. Professional Liability (Errors & Omissions)
Professional liability — also called Errors & Omissions (E&O) — covers claims that your organization's professional services caused harm. This coverage is critical for nonprofits providing counseling, education, healthcare, social services, legal aid, or financial assistance. If a client claims that your organization's advice or services caused them financial or personal harm, professional liability covers your legal defense and any resulting settlement or judgment.
4. Commercial Property Insurance
Commercial property insurance protects your owned or leased building, equipment, furniture, computers, and supplies. For nonprofits, this often includes coverage for donated property — equipment and supplies donated to your organization that have real replacement value. In Oregon and the American West, commercial property coverage should also address wildfire risk, which is an increasing concern for organizations operating in fire-prone areas of Central Oregon, Southern Oregon, and the broader intermountain West.
5. Workers' Compensation
Oregon law requires all employers — including nonprofits — to carry Workers' Compensation insurance if they have one or more paid employees, whether full-time, part-time, or seasonal. The penalty for non-compliance is severe: the Oregon Workers' Compensation Division can assess a penalty of up to twice the amount of the premium that should have been paid, and the organization remains personally liable for any claims that occur during the uninsured period.
Volunteers are generally not covered by Workers' Compensation in Oregon unless the nonprofit has specifically elected to extend coverage to them. Many nonprofits choose to purchase a separate Volunteer Accident policy to cover medical expenses for volunteers injured while performing their duties — a relatively inexpensive addition that can prevent significant goodwill damage and potential litigation.
6. Umbrella / Excess Liability
An umbrella policy provides an additional layer of liability protection above your primary general liability, D&O, and auto policies. For nonprofits with high public exposure, large events, or significant assets, umbrella coverage is essential. A $1 million umbrella policy typically costs $400–$800 per year for small nonprofits — one of the best values in commercial insurance. Insure Pacific also offers standalone umbrella insurance for organizations that need additional protection.
7. Cyber Liability Insurance
Nonprofits collect and store sensitive data — donor credit card information, client health records, employee Social Security numbers, and grant application data. This makes them attractive targets for cybercriminals, who increasingly view nonprofits as soft targets with limited IT security resources.
A data breach at an Oregon nonprofit can trigger notification obligations under Oregon's Consumer Identity Theft Protection Act (ORS 646A.600), credit monitoring costs, regulatory fines, and significant reputational damage. Cyber Liability insurance covers these costs — including forensic investigation, legal fees, notification expenses, and crisis communications support. For nonprofits processing online donations or maintaining donor databases, a minimum of $1 million in Cyber Liability coverage is recommended. Premiums for small nonprofits typically range from $500–$2,000 per year.
What Does Nonprofit Insurance Cost in Oregon?
Nonprofit insurance costs vary significantly based on organization size, activities, number of employees and volunteers, and the coverage limits selected. The table below provides general benchmarks for Oregon nonprofits in 2026.
| Coverage Type | Small Nonprofit (<$500K revenue) | Mid-Size Nonprofit ($500K–$2M) |
|---|---|---|
| General Liability ($1M/$2M) | $400–$900/yr | $900–$2,500/yr |
| Directors & Officers ($1M) | $800–$2,000/yr | $2,000–$5,000/yr |
| Workers' Compensation | $500–$1,500/yr | $2,000–$8,000/yr |
| Commercial Property | $300–$800/yr | $800–$3,000/yr |
| Cyber Liability ($1M) | $500–$1,200/yr | $1,200–$3,500/yr |
| Umbrella ($1M) | $400–$800/yr | $800–$2,000/yr |
| Full Package (bundled) | $2,000–$5,000/yr | $6,000–$18,000/yr |
These are general benchmarks only. Actual premiums depend on your specific operations, claims history, coverage limits, and carrier. Contact Insure Pacific for a free nonprofit insurance quote.
Get a Free Nonprofit Insurance Review
Our Oregon nonprofit insurance specialists compare 50+ carriers — including Nonprofits Insurance Alliance, Philadelphia Insurance, Markel, and The Hartford — to find the right combination of coverage and price for your organization. No obligation, no pressure.
Talk to a Nonprofit Insurance Specialist →Special Event Insurance for Oregon Nonprofits
Fundraising events are the lifeblood of many Oregon nonprofits. From the Crook County Fair to Bend's arts festivals to Sisters' folk music gatherings, nonprofits are at the center of the region's community calendar. But every event creates liability exposure — and many organizations discover too late that their standard general liability policy does not cover special events, particularly those involving alcohol service.
Oregon's liquor liability laws are strict. If your nonprofit serves alcohol at a fundraiser and a guest is later involved in an accident, your organization can be held liable under Oregon's Dram Shop Act. A Special Event Liquor Liability endorsement — or a standalone event policy — is essential for any fundraiser where alcohol is served. Insure Pacific's dedicated Non-Profits & Events coverage page covers the full range of event insurance options available to Oregon nonprofits.
Beyond liquor liability, special event insurance can cover cancellation or postponement due to weather or other unforeseen circumstances, damage to rented venues, and liability for vendors and contractors working at the event. For large events with attendance over 500 people, a standalone event policy is strongly recommended rather than relying on a general liability endorsement. For a comprehensive overview of event coverage options, see our Oregon Event Insurance Complete Guide.
Types of Oregon and American West Nonprofits We Insure
Insure Pacific works with a wide range of nonprofit organizations across Oregon and the American West. Our team understands the unique coverage needs of each type of organization, from small volunteer-run charities to large regional service organizations:
American West Considerations: Wildfire, Rural Operations, and Multi-State Coverage
Oregon nonprofits operating in fire-prone areas of Central Oregon, Southern Oregon, and the broader American West face insurance challenges that go beyond the standard nonprofit risk profile. Wildfire is an increasing concern for organizations that own or lease property in high-risk zones, operate outdoor programs, or host events in rural settings.
Commercial property policies for nonprofits in wildfire-prone areas should be reviewed carefully for exclusions, sublimits, and replacement cost provisions. Some carriers are restricting coverage or non-renewing policies in high-risk zones across Oregon, California, Idaho, Nevada, and other Western states. An independent agent with access to specialty markets can often find coverage when standard carriers decline.
For nonprofits operating across multiple Western states — whether running programs in Oregon and Idaho, or coordinating disaster relief across the region — multi-state coverage coordination is essential. Insure Pacific is licensed in 10 states across the American West and can structure a coverage program that follows your organization's operations wherever they take you. Our commercial insurance team has experience placing coverage for nonprofits operating in Oregon, Washington, Idaho, Nevada, California, Arizona, Montana, Wyoming, Colorado, and Utah.
How to Get the Right Nonprofit Insurance: A Step-by-Step Guide
Step 1: Conduct a Risk Assessment
Before approaching any insurer, document your organization's activities, assets, number of paid employees and volunteers, types of events you host, any owned or leased property, and the professional services you provide. This information drives every coverage decision and premium calculation.
Step 2: Prioritize D&O Coverage
If your organization has a board of directors — and every Oregon nonprofit does — D&O insurance should be your first priority. The personal liability exposure for board members is real and significant, and the cost of coverage is modest relative to the protection it provides.
Step 3: Review Your Event Calendar
For every event your organization hosts, confirm whether your general liability policy covers it — and whether you need additional event-specific coverage for alcohol service, large crowds, or high-value venues. Do this before the event, not after.
Step 4: Work with a Specialty Nonprofit Carrier
Standard commercial carriers often do not understand the unique risk profile of nonprofit organizations. Specialty nonprofit carriers — including Nonprofits Insurance Alliance (NIA), Philadelphia Insurance Companies, Markel, and GuideOne — offer policies specifically designed for the nonprofit sector, with broader coverage, lower premiums, and claims teams that understand your organization's mission.
Step 5: Use an Independent Agent
Specialty nonprofit markets are primarily distributed through independent agents. A captive agent or direct writer cannot access Nonprofits Insurance Alliance, Philadelphia Insurance, or Markel — they can only offer their own company's products. An independent agent like Insure Pacific can simultaneously quote your organization through multiple specialty carriers, compare coverage terms, and identify the program that best matches your specific needs and budget.
Frequently Asked Questions
What insurance does a nonprofit organization need in Oregon?
Most Oregon nonprofits need a combination of General Liability, Directors & Officers (D&O), Workers' Compensation (if they have paid staff), Commercial Property, and an Umbrella policy. Larger organizations may also need Professional Liability, Cyber Liability, and Crime/Fidelity coverage. The Nonprofit Association of Oregon recommends that all nonprofits carry at minimum D&O and General Liability coverage.
Are nonprofit board members personally liable in Oregon?
Yes, in many circumstances. Oregon's volunteer immunity statute (ORS 65.369) provides limited protection, but it does not cover gross negligence, actions outside the scope of board duties, or employment-related claims. D&O insurance is the primary protection for board members' personal assets.
Does a nonprofit need workers' compensation for volunteers?
Oregon law does not require workers' compensation for unpaid volunteers, but volunteers can still be injured while working for your organization. Many nonprofits purchase a separate Volunteer Accident policy to cover medical expenses for injured volunteers — a relatively inexpensive addition that protects both the volunteers and the organization's goodwill.
How much does nonprofit insurance cost in Oregon?
A basic nonprofit insurance package in Oregon typically starts at $2,000–$5,000 per year for small organizations with limited operations. Larger nonprofits with paid staff, owned property, and significant programming can expect to pay $6,000–$18,000+ annually. The Hartford reports an average BOP premium of approximately $836 per year for nonprofit customers.
Can Insure Pacific insure nonprofits operating in multiple Western states?
Yes. Insure Pacific is licensed in 10 states across the American West and can structure coverage programs for nonprofits operating across state lines. Contact our Bend, Prineville, or Brookings offices to discuss your organization's multi-state coverage needs.
Does nonprofit insurance cover fundraising events?
General liability may cover some claims arising from fundraising events, but coverage depends on the policy and the nature of the event. Events involving alcohol service, large crowds, or high-value venues typically require additional event-specific coverage. See our Non-Profits & Events page for a full overview of event coverage options.
Protect Your Mission, Your Board, and Your Community
Whether you're a small volunteer-run charity or a large regional service organization, Insure Pacific has the specialty nonprofit carriers and the independent agency expertise to build a comprehensive coverage program that fits your mission and your budget. Serving Oregon and the American West since 1935.
Our Licensed Coverage Area
States highlighted in blue are states where Insure Pacific holds an active insurance license.
Hover to highlight — click a state to visit its insurance page
Our Oregon Office Locations
Hover over a marker to see the office — click to visit their website.
Hover to highlight — click to visit that office's website
Ready to Get Protected?
Talk to a Local Oregon Insurance Expert
Insure Pacific has been serving Oregon families and businesses since 1935. We work with 50+ carriers so you get real options — not just one company's answer.
Related Articles
 Commercial Insurance
Multi-State Workers’ Compensation: Remote Employees, Traveling Crews, and Out-of-State Jobs
Read Article → Commercial Insurance
Import and Export Cargo Insurance: Ocean Freight, Ports, Customs, and Inland Transportation
Read Article → Commercial Insurance
Has Your Business Outgrown Its Insurance? Revenue, Payroll, New Locations, and New Services
Read Article → Commercial Insurance
Buying a Commercial Building: Insurance Questions to Answer Before Closing
Read Article →Get in Touch
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


