



Bundling Insurance Across Multiple States: How It Works When You Own Property in More Than One Place
Bundling Insurance Across Multiple States: How It Works When You Own Property in More Than One Place

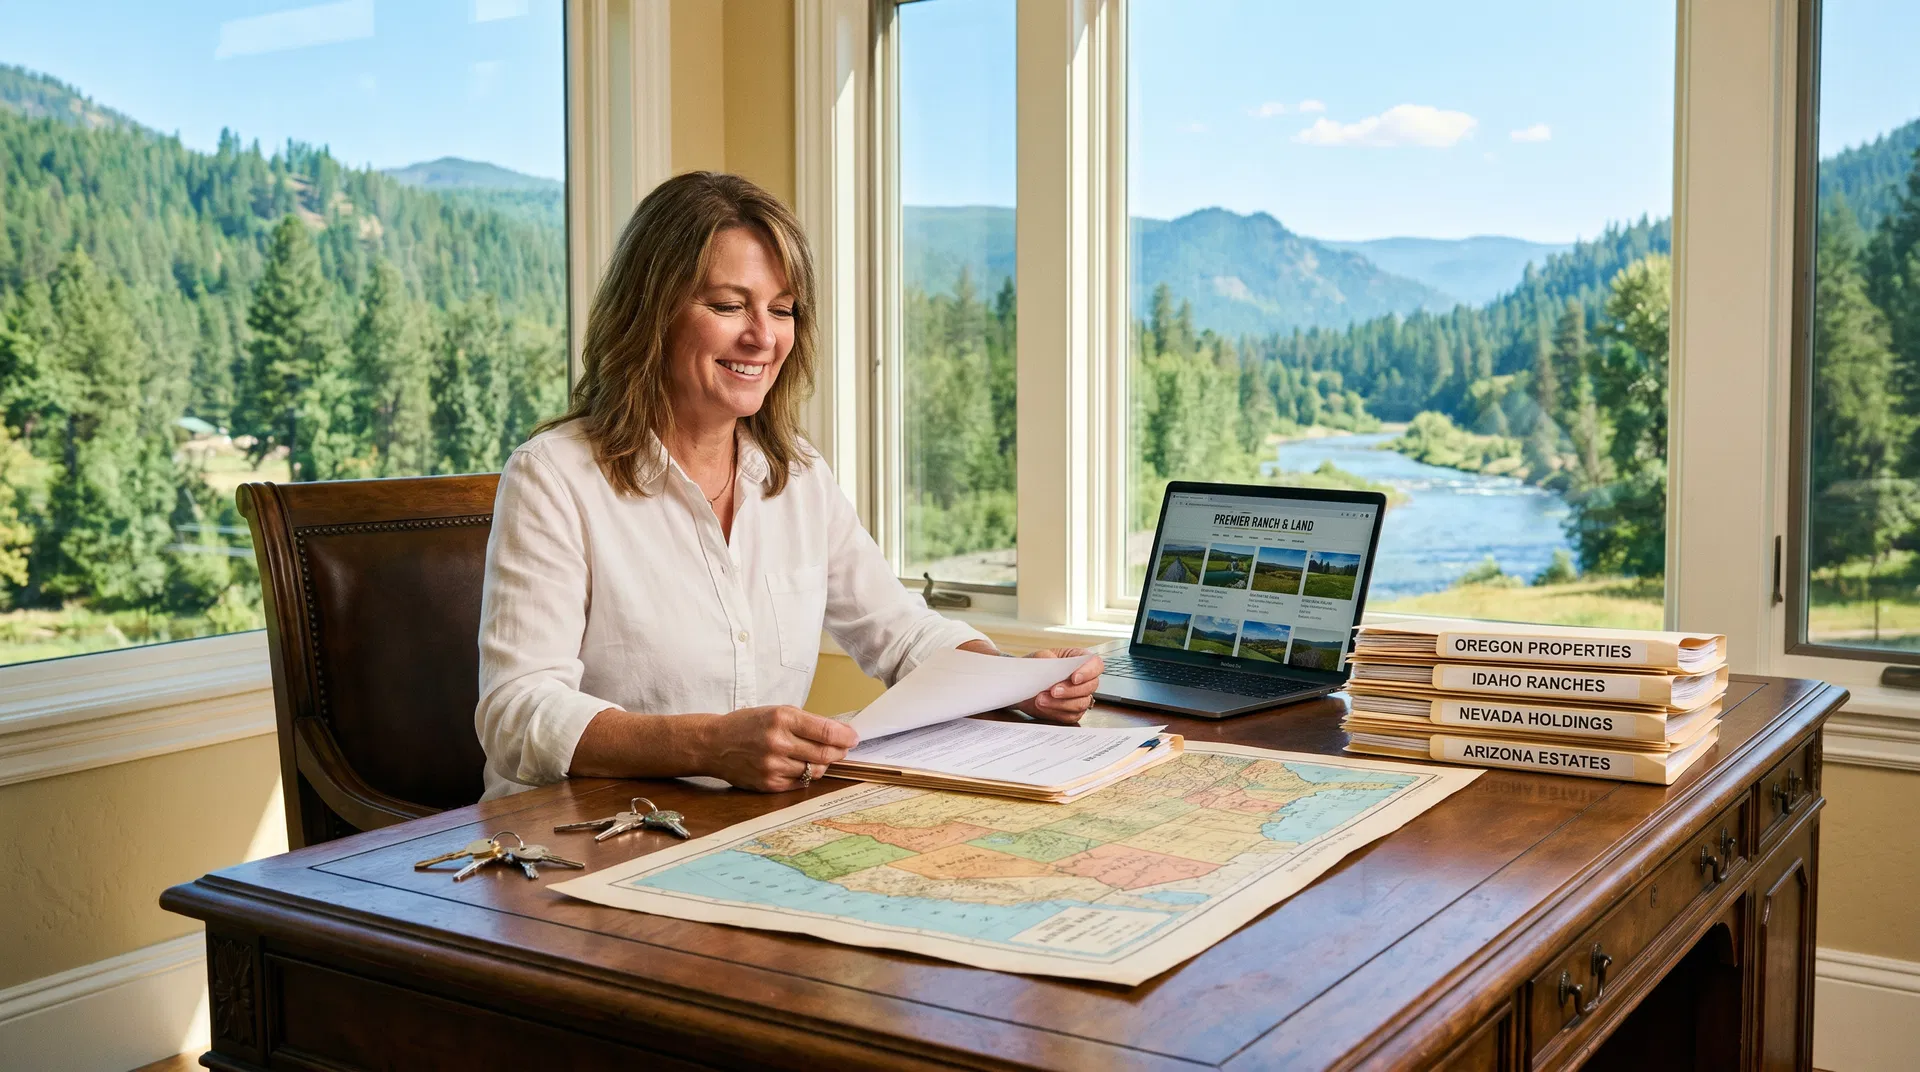
You own a home in Bend, Oregon. Maybe a vacation cabin in McCall, Idaho. A rental property in Henderson, Nevada. Perhaps a winter retreat outside Scottsdale, Arizona. You've worked hard to build this portfolio — but there's a good chance your insurance program hasn't kept pace with it. Multi-state property ownership creates a tangle of policy coordination challenges, coverage gaps, and missed bundling opportunities that most property owners don't discover until they file a claim.
The good news: Insure Pacific is licensed in all ten states across the American West, and we work with 50+ carriers who write policies in multiple states. That means one agent, one relationship, and a coordinated insurance strategy that covers everything you own — wherever it sits. This guide explains exactly how multi-state insurance works, where the gaps hide, and how to structure your coverage so nothing falls through the cracks.
The Most Common Multi-State Coverage Gap
The single most frequent problem we see with multi-state property owners: an umbrella policy purchased in Oregon that doesn't properly schedule the underlying policies on the Idaho cabin or Nevada rental. When a liability claim arises at the out-of-state property, the umbrella has no underlying policy to "stack on top of" — leaving the owner personally exposed for hundreds of thousands of dollars. This is entirely preventable with proper policy coordination.
Own Property in Multiple States? Let's Review Your Coverage.
Insure Pacific is licensed in Oregon, Idaho, Nevada, Arizona, Washington, California, Utah, Colorado, and Wyoming. One call covers everything you own across the American West.
Why Multi-State Property Ownership Creates Insurance Complexity
Insurance is fundamentally a state-regulated product. Each state has its own insurance code, its own required policy forms, its own filing requirements for carriers, and its own rules about what must be covered and what can be excluded. When you own property in Oregon and Idaho, you're not just dealing with two different addresses — you're dealing with two different regulatory environments, two different risk profiles, and potentially two different carriers who may or may not coordinate with each other.
The complexity compounds when you add a rental property in Nevada or a winter home in Arizona. Nevada has its own landlord insurance requirements and tenant protection laws. Arizona's extreme heat creates unique property risks — roof damage, HVAC failure, and monsoon flooding — that Oregon carriers may not fully understand or price correctly. Each state's insurance market also has different carrier availability: a carrier that writes excellent homeowners insurance in Oregon may not even be licensed in Nevada, or may offer significantly different coverage terms there.
| State | Avg. Annual HO Premium | Top Risks | Key Coverage Notes |
|---|---|---|---|
| Oregon | $712/yr | Wildfire, earthquake, wind | Wildfire surcharges in high-risk zones; earthquake separate policy |
| Idaho | $890/yr | Wildfire, snow load, flooding | Cabin/seasonal vacancy clauses; flood separate NFIP policy |
| Nevada | $980/yr | Flash flood, wind, theft | Landlord policy required for rentals; loss of rent coverage important |
| Arizona | $1,150/yr | Monsoon, wildfire, heat damage | Roof age matters; HVAC breakdown coverage often needed |
| Washington | $830/yr | Earthquake, wind, landslide | Earthquake coverage strongly recommended; landslide exclusions common |
Average annual homeowners insurance premiums per InsuranceGeek 2026 data. Actual rates vary by property value, location, construction, and claims history.
The Three Types of Multi-State Property Situations
Not all multi-state property portfolios are the same. The right insurance strategy depends on how you use each property, how often you're there, and whether you generate rental income. Here are the three most common situations Insure Pacific clients face:
Primary Home + Vacation Property
The most common scenario: a primary residence in Oregon and a seasonal cabin in Idaho, a beach house on the Oregon Coast, or a ski condo in Colorado. The vacation property is typically unoccupied for extended periods, which creates vacancy-related exclusions that many owners don't realize exist. Most standard homeowners policies exclude or severely limit coverage after 30–60 days of vacancy.
Solution: A dedicated second home or seasonal property policy with a vacancy endorsement, coordinated with your primary home policy under a single umbrella.
Primary Home + Rental Property
Owning a rental property in Nevada or Arizona while living in Oregon is increasingly common among American West investors. A standard homeowners policy explicitly excludes rental activity — if you're collecting rent and a tenant is injured on the property, your Oregon homeowners policy will not respond. You need a dedicated landlord or dwelling fire policy in the state where the rental is located.
Solution: A landlord insurance policy in the rental property's state, with loss of rental income coverage and liability limits that coordinate with your umbrella.
Multi-Property Portfolio
Some Insure Pacific clients own three or more properties across multiple states — a primary home, a vacation cabin, a rental, and perhaps a small commercial property or farm. At this level, policy coordination becomes critical. You need an agent who can see the full picture: which carriers write in which states, how umbrella limits stack across all underlying policies, and where the gaps are.
Solution: A portfolio review with a multi-state licensed agent who can place all properties with carriers that coordinate, and structure a single umbrella over the entire portfolio.
How Bundling Works — and Where It Breaks Down
"Bundling" in the multi-state context means more than just getting a discount for having two policies with the same carrier. True multi-state bundling means your policies are structured so they coordinate with each other — particularly your umbrella policy, which is designed to provide excess liability coverage over all your underlying home, auto, and rental policies.
Here's where it commonly breaks down: you purchase an umbrella policy in Oregon, and it lists your Oregon home and your Oregon auto as the underlying policies. You then purchase a separate homeowners policy for your Idaho cabin through a different carrier or agent. Because the Idaho policy isn't listed as an underlying policy on your umbrella, the umbrella won't respond to a claim at the Idaho property — even though you assumed you were covered. This gap can leave you personally exposed for the full amount of a liability judgment.
How a Properly Structured Multi-State Umbrella Works
Umbrella Policy ($1M–$5M)
Single umbrella policy listing ALL underlying policies across all states as scheduled underlying coverage
Oregon Primary Home ($300K liability)
Homeowners policy — Oregon carrier, Oregon address
Idaho Cabin ($300K liability)
Seasonal/second home policy — Idaho-licensed carrier, Idaho address — MUST be listed on umbrella
Nevada Rental ($300K liability)
Landlord/dwelling fire policy — Nevada-licensed carrier, Nevada address — MUST be listed on umbrella
Oregon Auto ($250K/$500K liability)
Auto policy — typically covers you in all 50 states automatically
When a claim exceeds the underlying policy limit, the umbrella activates — but only if that underlying policy is properly scheduled. An agent who only sees one state's policies will miss this coordination requirement.
State-by-State: What Changes When You Cross the Border
Each state in the American West has unique risk characteristics and insurance market conditions that directly affect your coverage options and premiums. Understanding these differences helps you make smarter decisions about how to structure coverage for each property.
Oregon
Wildfire Risk Is the Defining Issue
Oregon's insurance market has been significantly reshaped by wildfire risk. Properties in high-risk zones — including much of Central Oregon, the Rogue Valley, and the Cascades foothills — may face surcharges, coverage restrictions, or non-renewal from standard carriers. Oregon also sits on the Cascadia Subduction Zone, meaning earthquake risk is real but almost never covered by a standard homeowners policy. If your Oregon home is your primary residence, make sure your policy addresses both wildfire and earthquake exposure.
Read our Oregon Wildfire Insurance GuideIdaho
Cabin and Seasonal Property Vacancy Rules
Idaho is a major destination for Oregon vacation property owners — McCall, Coeur d'Alene, Sun Valley, and the Sawtooth region all attract second-home buyers. The key insurance issue with Idaho cabins is vacancy. Most standard homeowners policies exclude or severely limit coverage after 30–60 days of vacancy, and a seasonal cabin that sits empty from October through May may be considered vacant under your policy's definition. You need a policy specifically designed for seasonal or vacation properties, with a vacancy endorsement that covers the property year-round.
See our Vacation Cabin Insurance pageNevada
Landlord Policies Are Non-Negotiable for Rentals
Nevada is a popular destination for Oregon investors purchasing rental properties in Las Vegas, Henderson, and Reno. A standard homeowners policy will not cover a property where tenants are paying rent — the moment you collect rent, you need a landlord or dwelling fire policy. Nevada landlord policies should include loss of rental income coverage (which pays your rent if the property becomes uninhabitable due to a covered loss), liability coverage, and ideally a tenant damage endorsement. Nevada law also has specific landlord-tenant provisions that affect your liability exposure.
Learn about Landlord InsuranceArizona
Heat, Monsoons, and Roof Age Restrictions
Arizona presents unique property risks that Pacific Northwest homeowners often underestimate. Monsoon season (July–September) brings flash flooding, high winds, and hail that can cause significant roof damage. Arizona's extreme heat accelerates roof deterioration — many Arizona carriers restrict coverage or require higher deductibles for roofs over 10–15 years old. HVAC systems are critical infrastructure in Arizona, and equipment breakdown coverage is worth adding. If you're buying an Arizona vacation home or rental, have the roof inspected and understand the carrier's age restrictions before you bind coverage.
Explore Homeowners Insurance optionsThe Bundling Discount Question: Can You Actually Save Money?
Multi-policy discounts are real, but they work differently in a multi-state context than most people expect. Within a single state, bundling your home and auto with the same carrier typically saves 10–25% on both policies. Across state lines, the savings are more nuanced — because not every carrier writes in every state, and the carrier that's best for your Oregon home may not be competitive in Idaho or Nevada.
The more meaningful financial benefit of multi-state coordination isn't always the bundling discount — it's avoiding the cost of a claim that falls through a coverage gap. A single uninsured liability claim at your Idaho cabin could cost $200,000–$500,000 or more. The premium savings from proper coordination (and avoiding gaps) dwarf any bundling discount you might get from a single carrier.
That said, some national carriers — including several in Insure Pacific's 50+ carrier network — do write policies in multiple western states and offer meaningful multi-state discounts when you place all your properties with them. Whether that's the right approach depends on whether that carrier is competitive in each state where you own property. This is exactly the kind of analysis your Insure Pacific agent can run for you.
| Strategy | Potential Savings | Best For | Trade-offs |
|---|---|---|---|
| Single carrier, all states | 10–25% multi-policy discount | Owners with 2–3 properties in states where carrier is competitive | Carrier may not be best option in every state |
| Best carrier per state, coordinated umbrella | Optimal coverage per property; umbrella savings | Owners with 3+ properties or complex risk profiles | Requires agent who can coordinate across carriers |
| Home + auto bundle, separate property policies | 10–20% on home/auto bundle | Owners whose out-of-state properties have unique risks | Umbrella coordination still required |
| Portfolio with commercial umbrella | Significant liability protection; often lower total cost | Owners with rental properties or LLCs | More complex; requires commercial lines expertise |
Insure Pacific's 10-State Footprint: Why It Matters for You
Most insurance agencies are licensed in one or two states. When you own property in three or four states and call an agent who's only licensed in Oregon, they can help you with your Oregon property — but they legally cannot advise you on your Idaho cabin, your Nevada rental, or your Arizona winter home. You end up with multiple agents who don't talk to each other, policies that don't coordinate, and no one who sees the full picture.
Insure Pacific is licensed in Oregon, Idaho, Nevada, Arizona, Washington, California, Utah, Colorado, and Wyoming. That means one agent who can review all your properties, identify every gap, and place coverage with carriers who coordinate across state lines. We've been doing this since 1935, and our team of licensed agents has deep experience with the specific risks of each western state.
Our umbrella specialists understand how to structure excess liability coverage that properly schedules all your underlying policies — regardless of which state they're in or which carrier wrote them. And because we work with 50+ carriers, we can find the right combination for your specific portfolio rather than forcing everything into a single carrier's box.
Is Your Umbrella Policy Covering All Your Properties?
Most multi-state property owners have at least one property that isn't properly scheduled on their umbrella. A 20-minute policy review with an Insure Pacific agent can identify the gaps and fix them before a claim exposes them.
Special Situations: LLCs, Trusts, and Inherited Properties
Many multi-state property owners hold their out-of-state properties in LLCs or trusts for asset protection and estate planning purposes. This creates an additional layer of insurance complexity that is frequently overlooked.
When a property is owned by an LLC, a standard personal homeowners or landlord policy may not cover it — because the named insured on the policy is you personally, not the LLC. If a claim arises and the property is titled to the LLC, the carrier may deny coverage on the grounds that the insured doesn't have an insurable interest in the property. The solution is to name the LLC as an additional insured or named insured on the policy, or to purchase a commercial property policy in the LLC's name.
Similarly, properties held in trusts — particularly revocable living trusts — need to be reviewed to ensure the trust is properly named on the policy. Most carriers can accommodate this with a simple endorsement, but it has to be done proactively. An inherited property that hasn't been re-titled or re-insured after the original owner's death is another common gap we see during portfolio reviews.
Multi-State Property Insurance Checklist
All properties have active, in-force policies in their respective states
Each out-of-state property has a policy appropriate for its use (primary, vacation, rental)
Vacation/seasonal properties have vacancy endorsements or seasonal policies
Rental properties have landlord/dwelling fire policies, not homeowners policies
All underlying policies are listed as scheduled underlying coverage on your umbrella
Umbrella limits are sufficient to cover your total asset exposure across all states
LLC-owned properties are named correctly on their policies (LLC as named insured)
Trust-owned properties have the trust named on the policy via endorsement
Earthquake coverage is in place for properties in seismic zones (OR, WA, ID)
Flood coverage (NFIP or private) is in place for properties in flood zones
Wildfire risk has been assessed for all western properties
You have a single agent who can see and coordinate all policies
What to Expect from a Multi-State Insurance Review
When you contact Insure Pacific for a multi-state portfolio review, here's what the process looks like. First, we'll ask you to share your current policies for all properties — declarations pages are sufficient. We'll review each policy for coverage adequacy, vacancy clauses, named insured accuracy, and whether the property type matches the policy type. We'll then look at your umbrella policy and verify that all underlying policies are properly scheduled.
From there, we'll identify any gaps and present options. In some cases, the fix is a simple endorsement on an existing policy. In others, we may recommend replacing a policy with a better-suited product, or adding a new policy for a property that was previously uninsured or underinsured. We'll also look at whether consolidating some policies with a single multi-state carrier makes sense for your portfolio.
The goal is a coordinated insurance program where every property is properly covered, every policy coordinates with your umbrella, and you have a single point of contact who understands your full picture. For most multi-state property owners, this kind of review surfaces at least one significant gap — and often several. The cost of fixing those gaps is almost always far less than the cost of discovering them during a claim.
Frequently Asked Questions
Do I need a separate insurance agent for each state where I own property?
Not if you work with an agent licensed in all the states where you own property. Insure Pacific is licensed in Oregon, Idaho, Nevada, Arizona, Washington, California, Utah, Colorado, and Wyoming — so one agent can handle your entire western portfolio. If you own property in a state outside our footprint, we can refer you to a trusted agent in that state and coordinate with them on your umbrella.
Does my Oregon homeowners policy cover my Idaho vacation cabin?
No. A homeowners policy covers only the specific property listed on the policy — your Oregon address. Your Idaho cabin needs its own separate policy, written by a carrier licensed in Idaho and appropriate for a seasonal or vacation property. The most common mistake is assuming your Oregon policy extends to other properties you own.
Can one umbrella policy cover properties in multiple states?
Yes — a personal umbrella policy is designed to provide nationwide coverage and can cover properties in multiple states. However, it only covers the properties that are listed as underlying policies on the umbrella. If your Idaho cabin or Nevada rental isn't listed, the umbrella won't respond to claims at those properties. This is the most important coordination step in a multi-state portfolio.
I hold my rental properties in LLCs. Does that affect my insurance?
Yes, significantly. A standard personal homeowners or landlord policy may not cover a property owned by an LLC, because the named insured is you personally, not the LLC. You need to either name the LLC as an additional insured on the policy, or purchase a commercial property policy in the LLC's name. This is a common gap that only surfaces at claim time — review your policy language carefully.
What's the difference between a second home policy and a landlord policy?
A second home or vacation property policy covers a property you own and use personally but don't rent out (or rent only occasionally). A landlord or dwelling fire policy covers a property you rent to tenants on a regular basis. The key difference is that landlord policies include loss of rental income coverage and are designed for the liability exposure of a landlord-tenant relationship. Using a second home policy for a rental property — or vice versa — can result in claim denial.
How much does it cost to insure properties in multiple states?
Costs vary widely by state, property type, value, and risk factors. As a general benchmark, a vacation cabin in Idaho might run $800–$1,500/year, a rental property in Nevada $1,000–$2,000/year, and an Arizona winter home $1,200–$2,500/year. Adding a personal umbrella over your entire portfolio typically costs $300–$600/year for $1M in coverage — one of the best values in insurance. Insure Pacific will shop 50+ carriers to find the best combination for your specific portfolio.
Ready to Coordinate Your Multi-State Insurance?
Insure Pacific has been serving Oregon and the American West since 1935. We're licensed in 10 states, work with 50+ carriers, and specialize in building coordinated insurance programs for multi-state property owners. Let's review your portfolio and make sure everything is covered — wherever it is.
Our Licensed Coverage Area
States highlighted in blue are states where Insure Pacific holds an active insurance license.
Hover to highlight — click a state to visit its insurance page
Our Oregon Office Locations
Hover over a marker to see the office — click to visit their website.
Hover to highlight — click to visit that office's website
Ready to Get Protected?
Talk to a Local Oregon Insurance Expert
Insure Pacific has been serving Oregon families and businesses since 1935. We work with 50+ carriers so you get real options — not just one company's answer.
Related Articles
 Personal Insurance
Full-Time RV Insurance: When Your Motorhome Becomes Your Primary Home
Read Article → Personal Insurance
ADU Insurance: Is Your Backyard Cottage Covered by Your Homeowners Policy?
Read Article → Personal Insurance
Water Damage Insurance: Hidden Leaks, Sewer Backups, Service Lines, Sump Pumps, Mold, and Smart Shutoff Devices
Read Article → Personal Insurance
Home Insurance Replacement Cost in 2026: Why Rebuilding Your Home Could Cost More Than Its Market Value
Read Article →Get in Touch
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


